Banking Beyond the Banking App
Building a new bank is one challenge. Convincing people to use it is another.
Rather than asking customers to download another banking app, we explored how banking could become part of the digital ecosystems they already used.
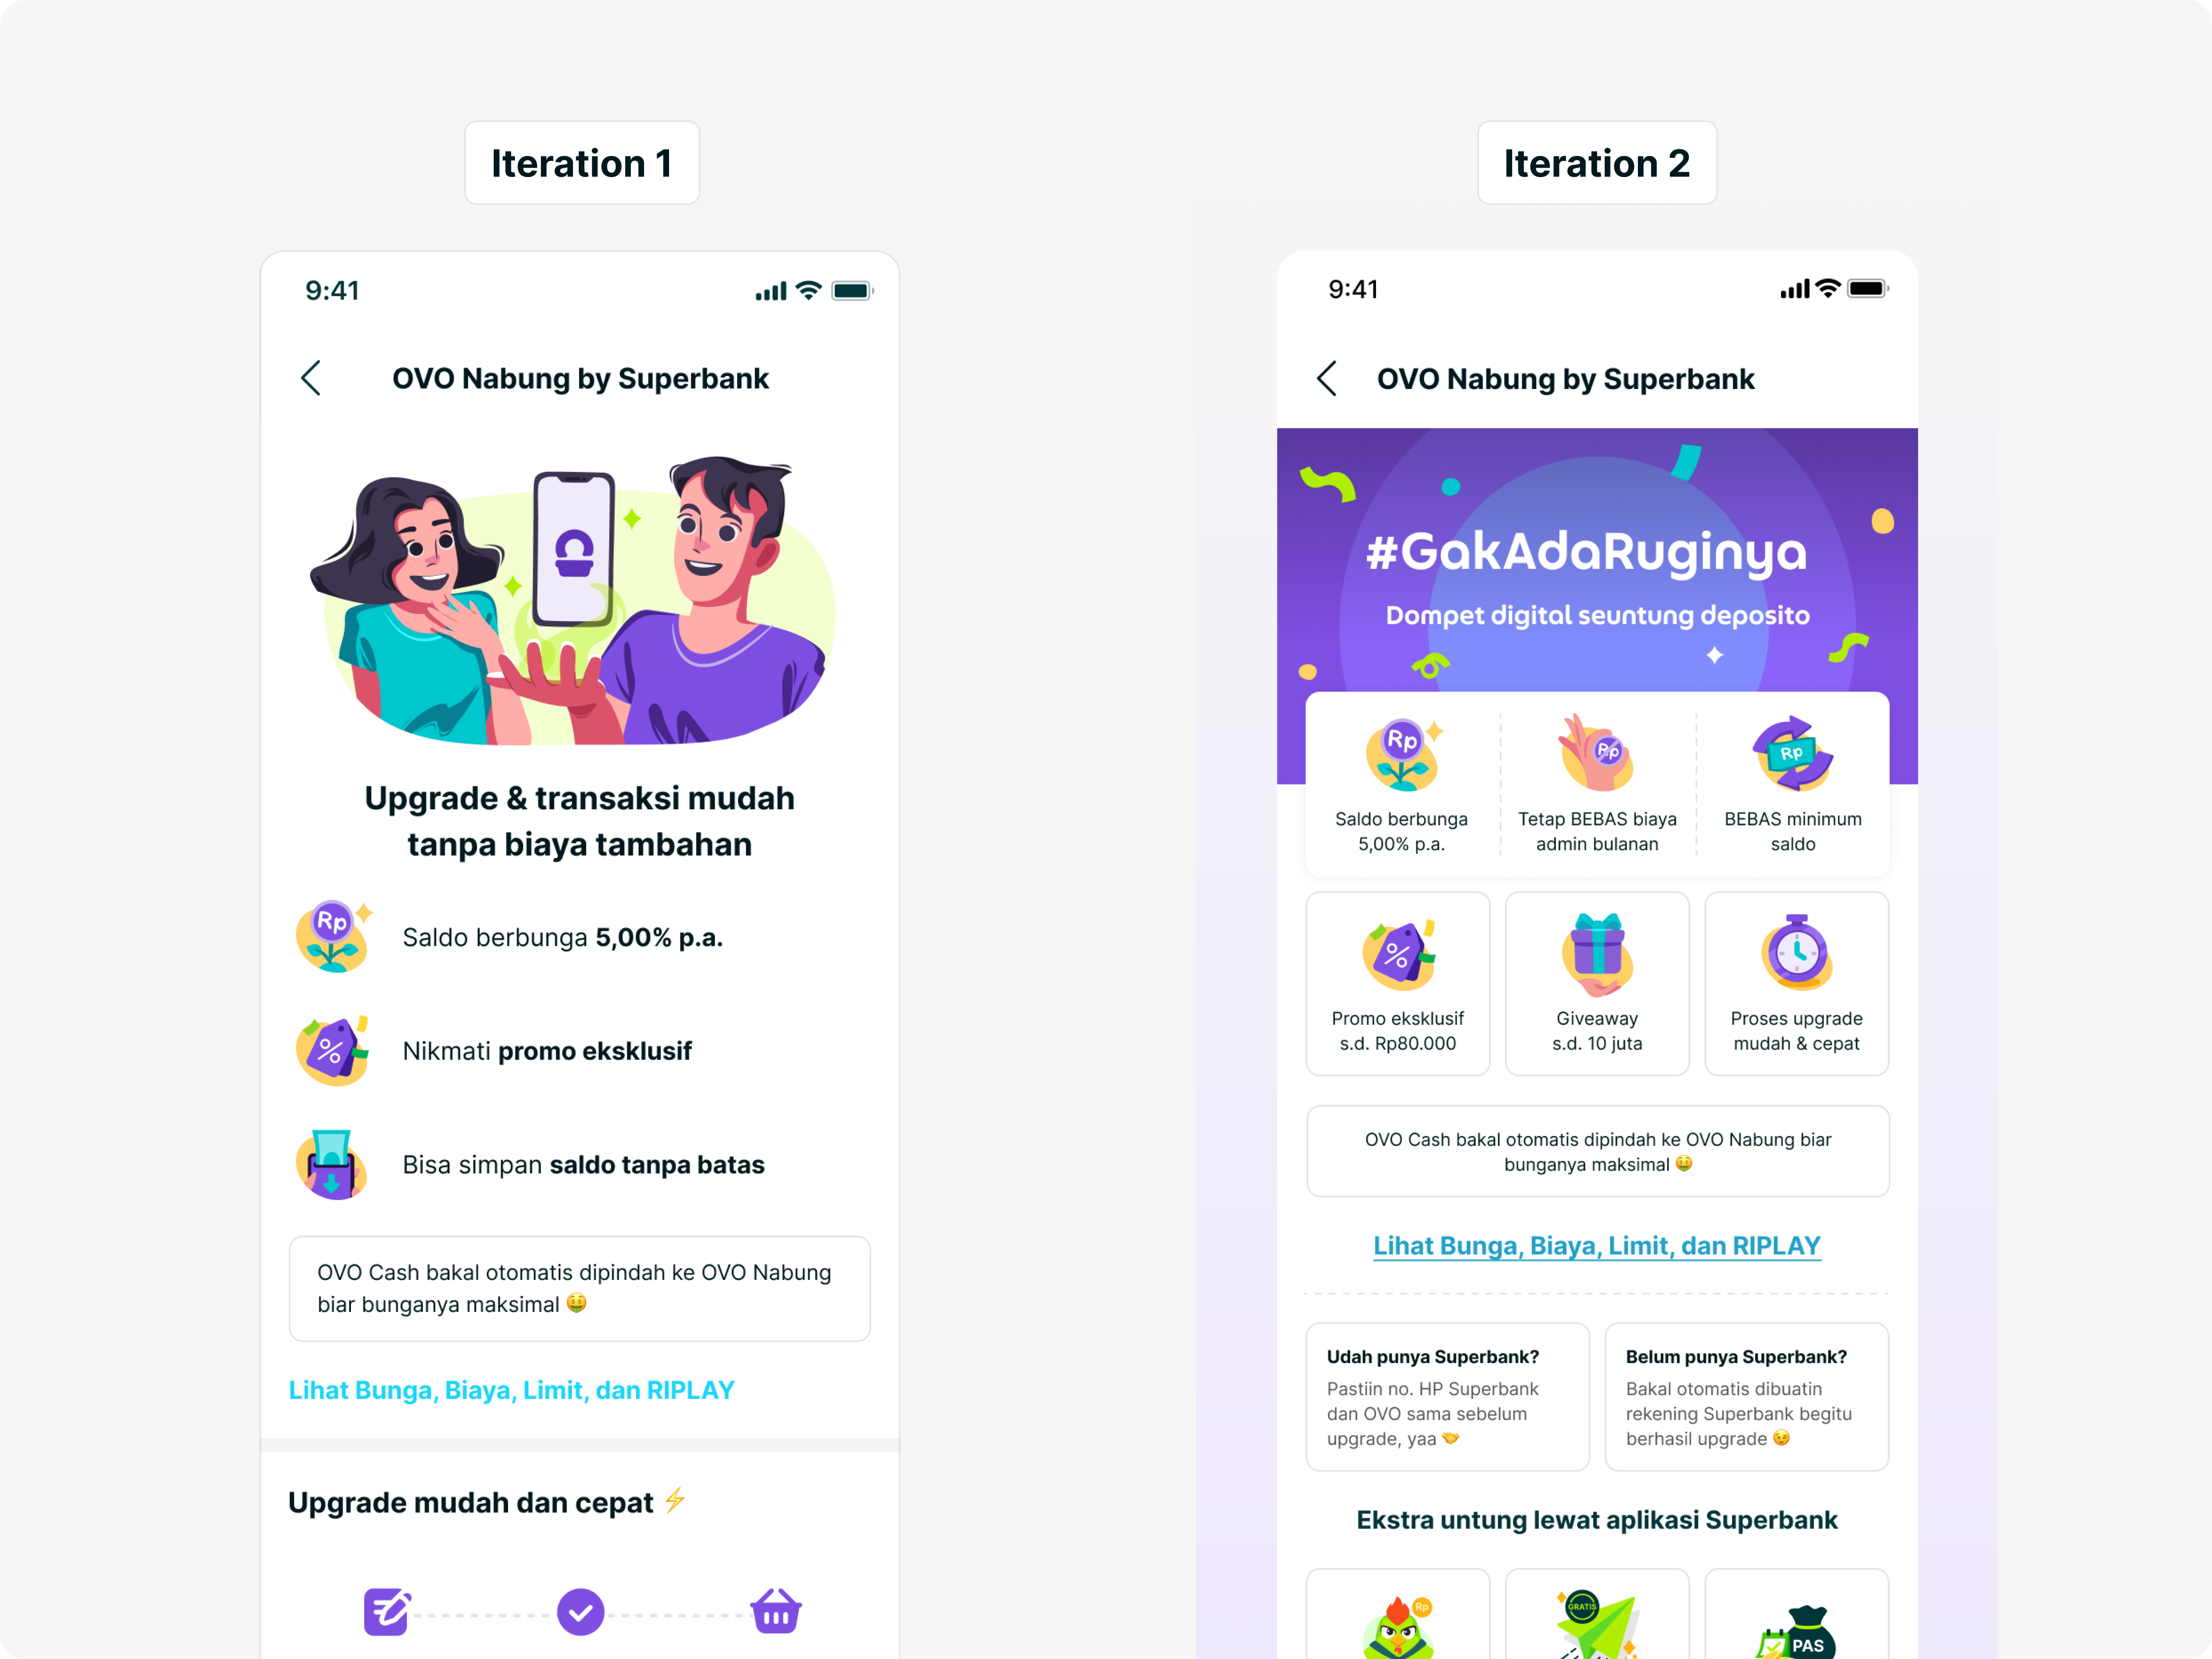
OVO Nabung: From E-Wallet to Banking
OVO was already one of Indonesia's largest digital wallets. The challenge was introducing banking services to existing users without adding unnecessary friction.
OVO Nabung became the first major project I led at Superbank, covering the end-to-end experience from onboarding and account linking to everyday banking within the OVO ecosystem.
The goal was to make banking feel like a natural extension of something customers already knew.
Impact
1M+ users in under one year
60% of Superbank users are from OVO Nabung
Grab Ecosystem: Making Banking Feel Seamless
Grab was already part of millions of Indonesians' daily routines. But introducing banking into an existing ecosystem came with its own challenges, particularly around onboarding, account linking, and communicating the value of a new bank.
Building on what we learned from OVO Nabung, I led improvements to Grab onboarding and account linking.
The focus was on identifying major drop-off points, refining the customer value proposition, and creating a more consistent experience across ecosystem partners.
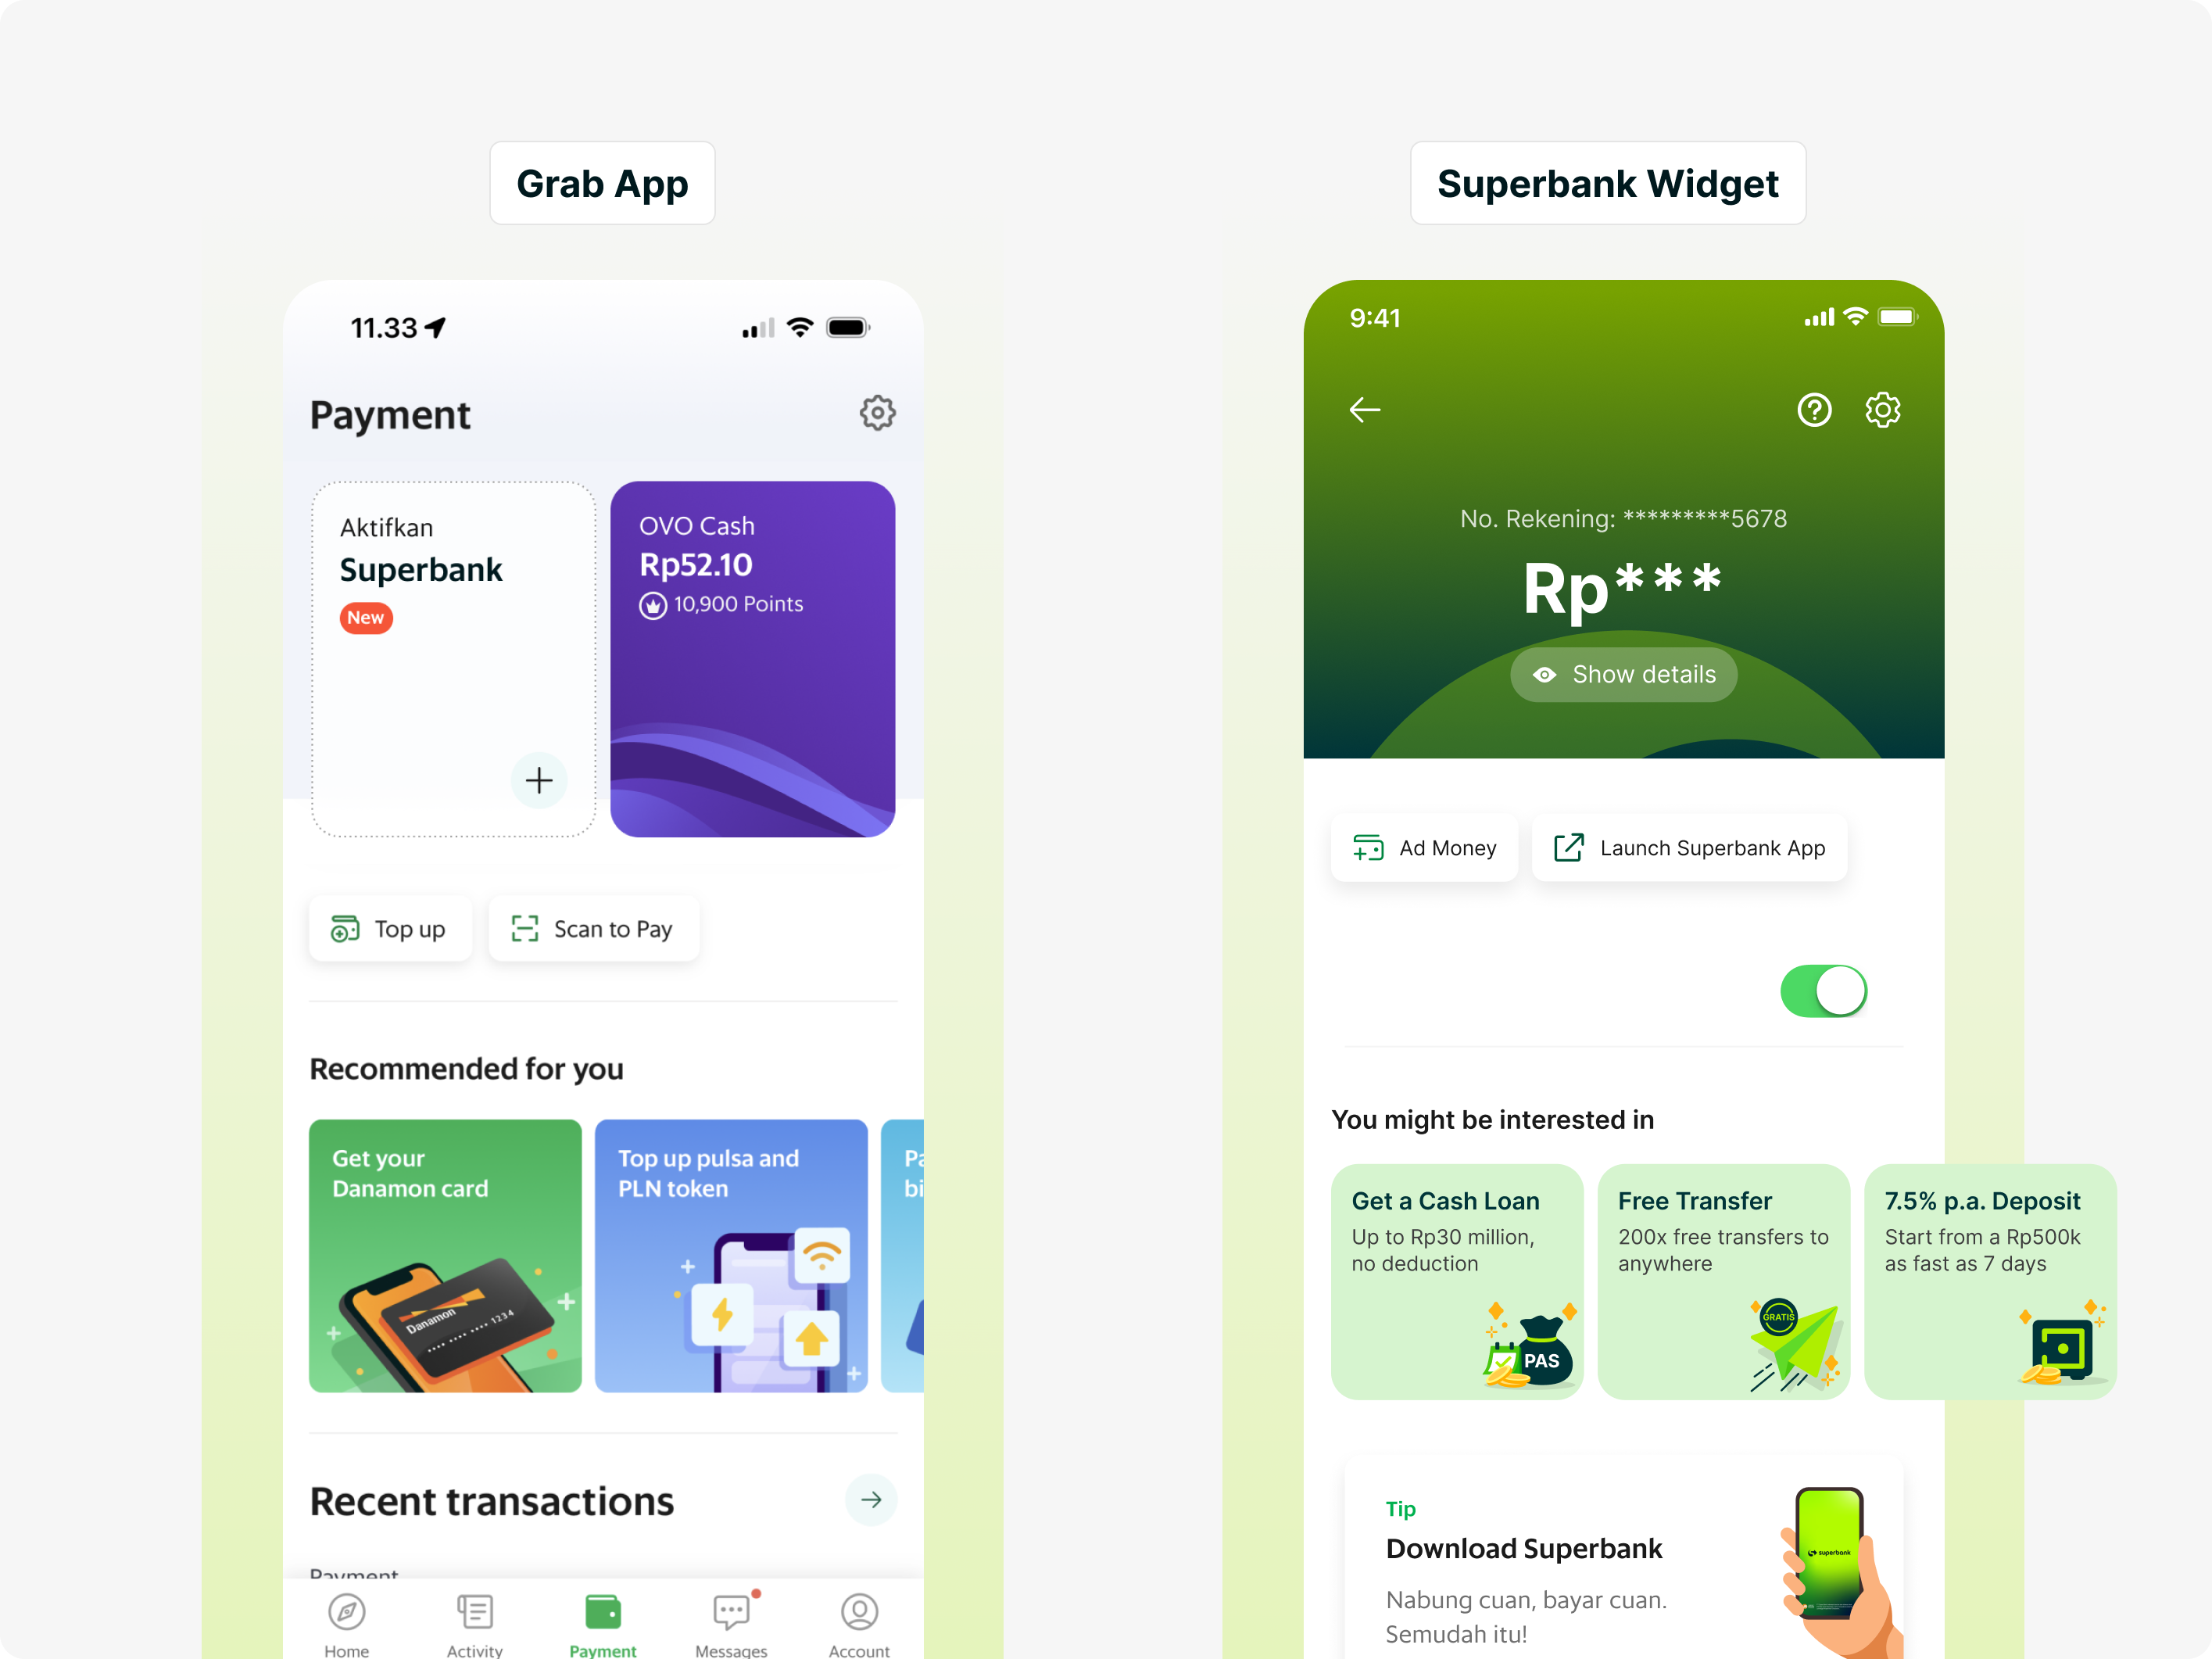
I led work on product discovery in the Grab app, including a cross-selling widget for Superbank products.
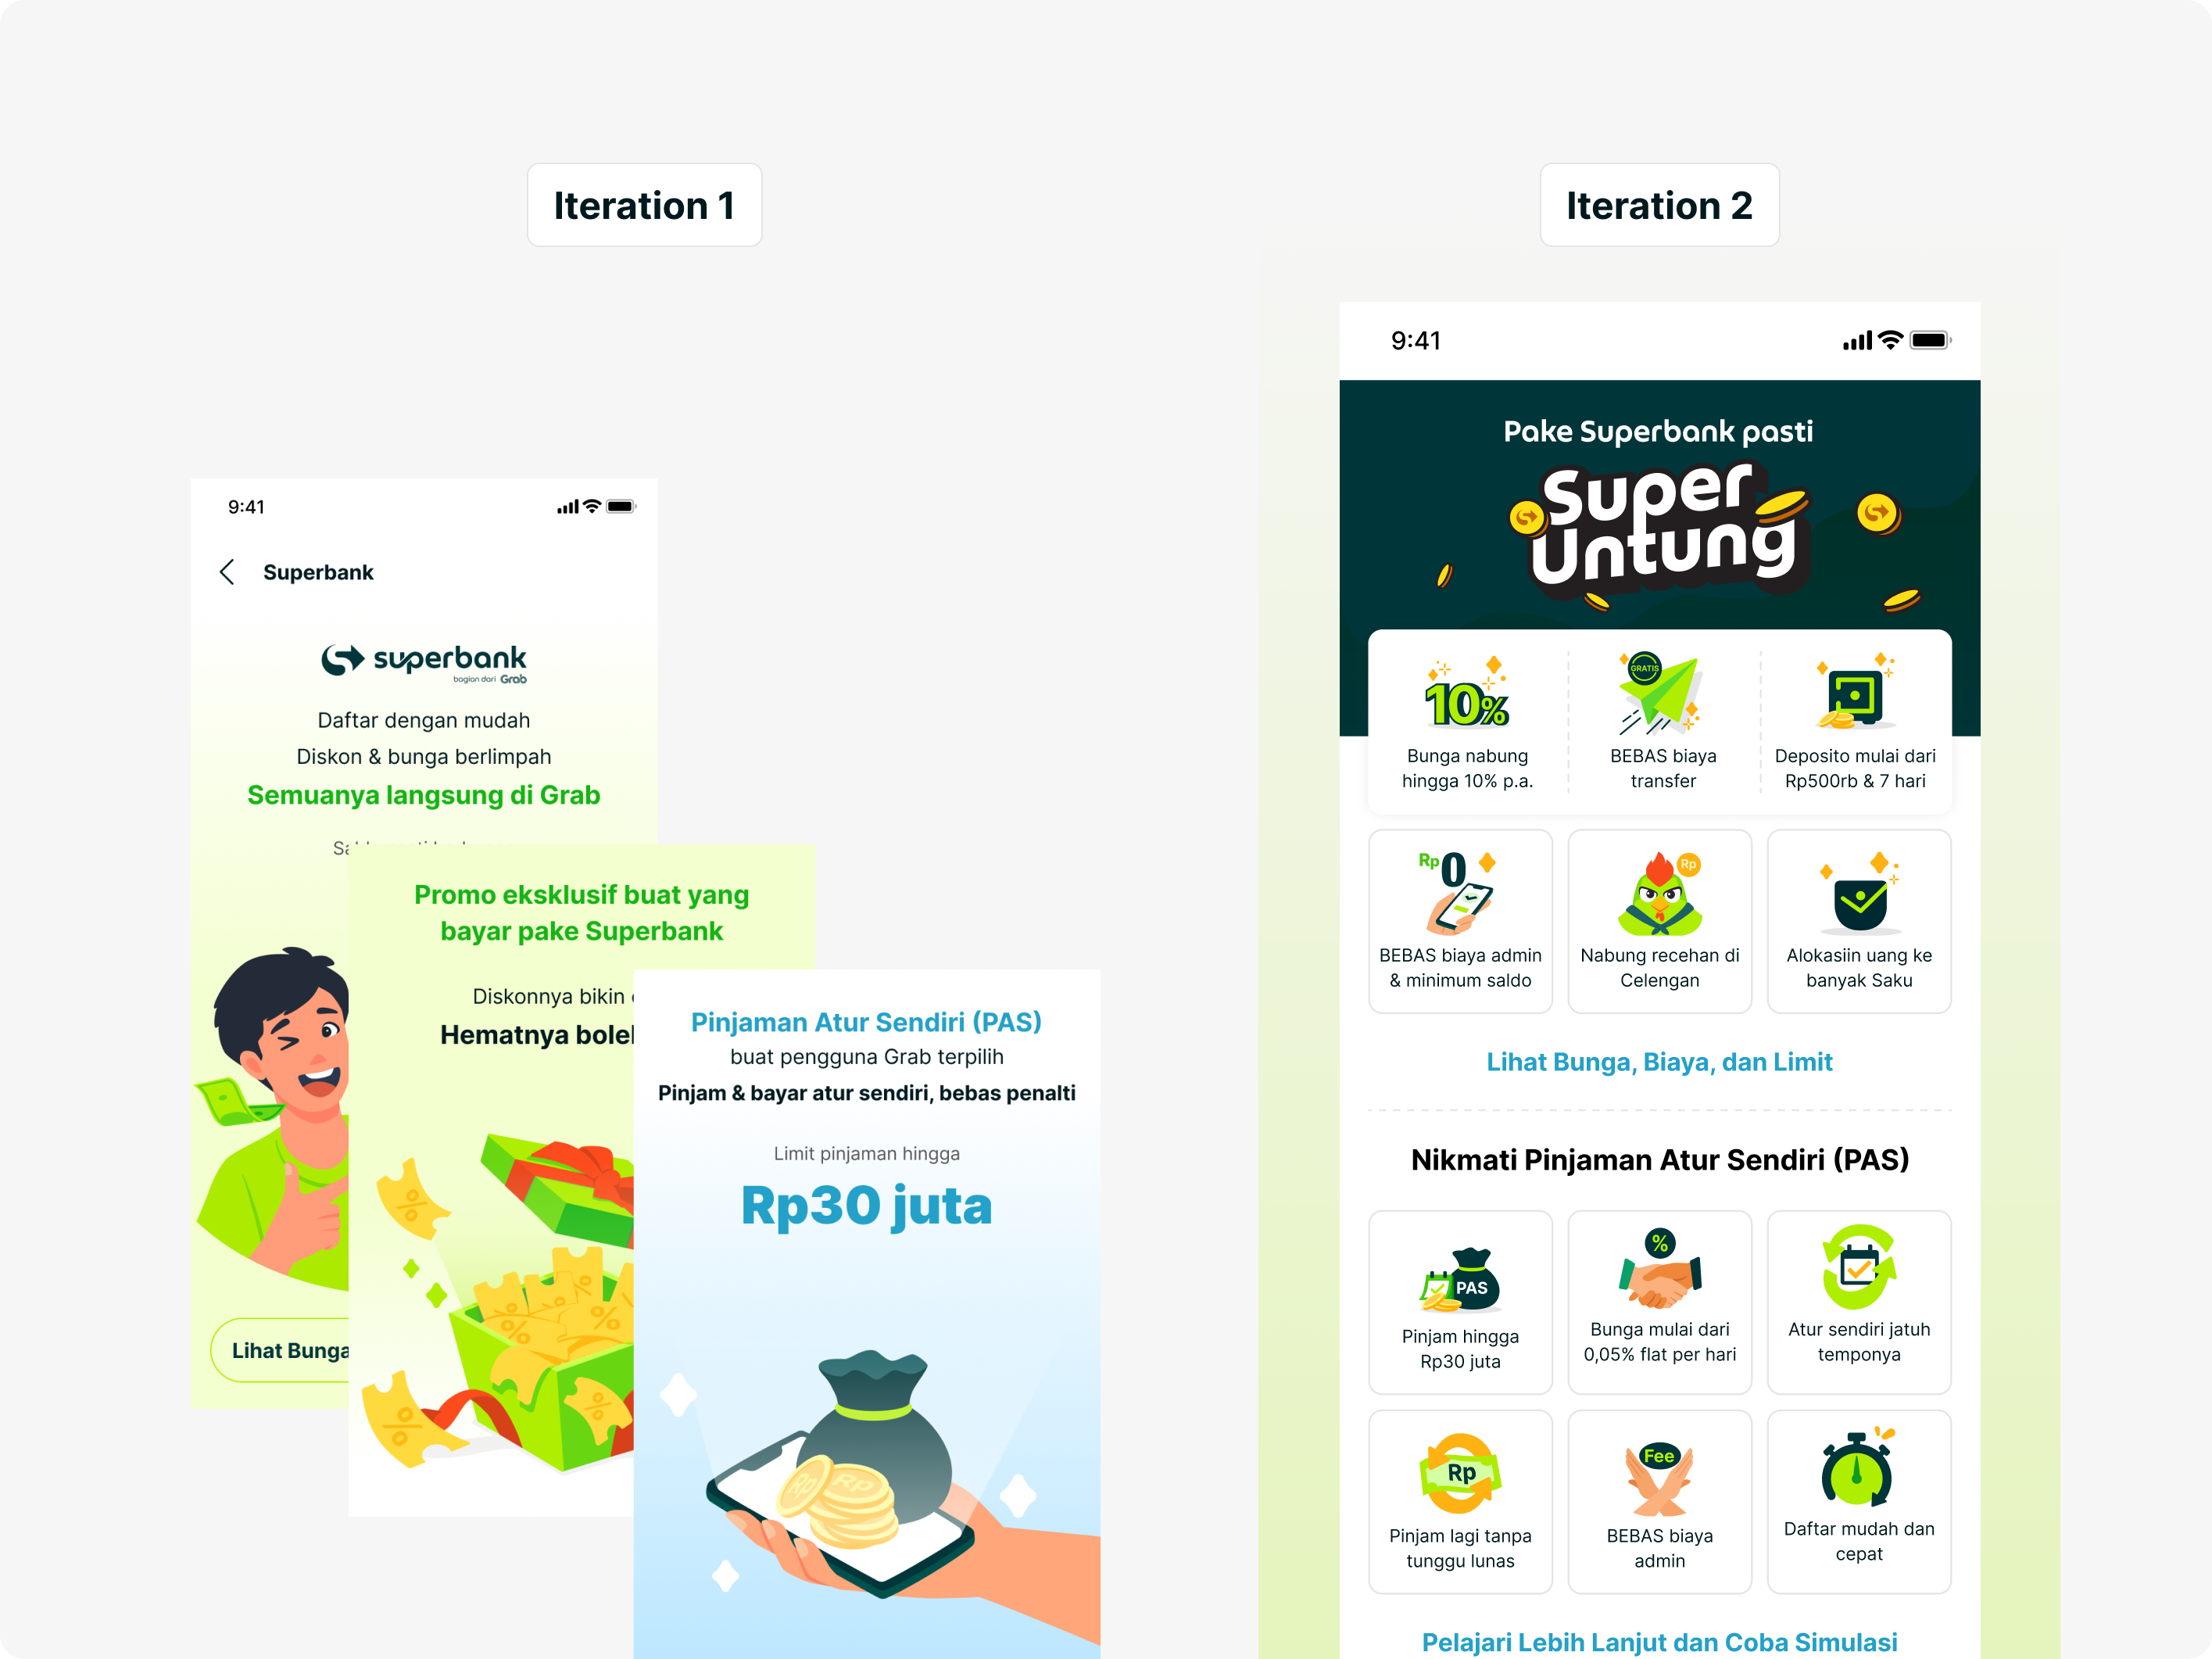
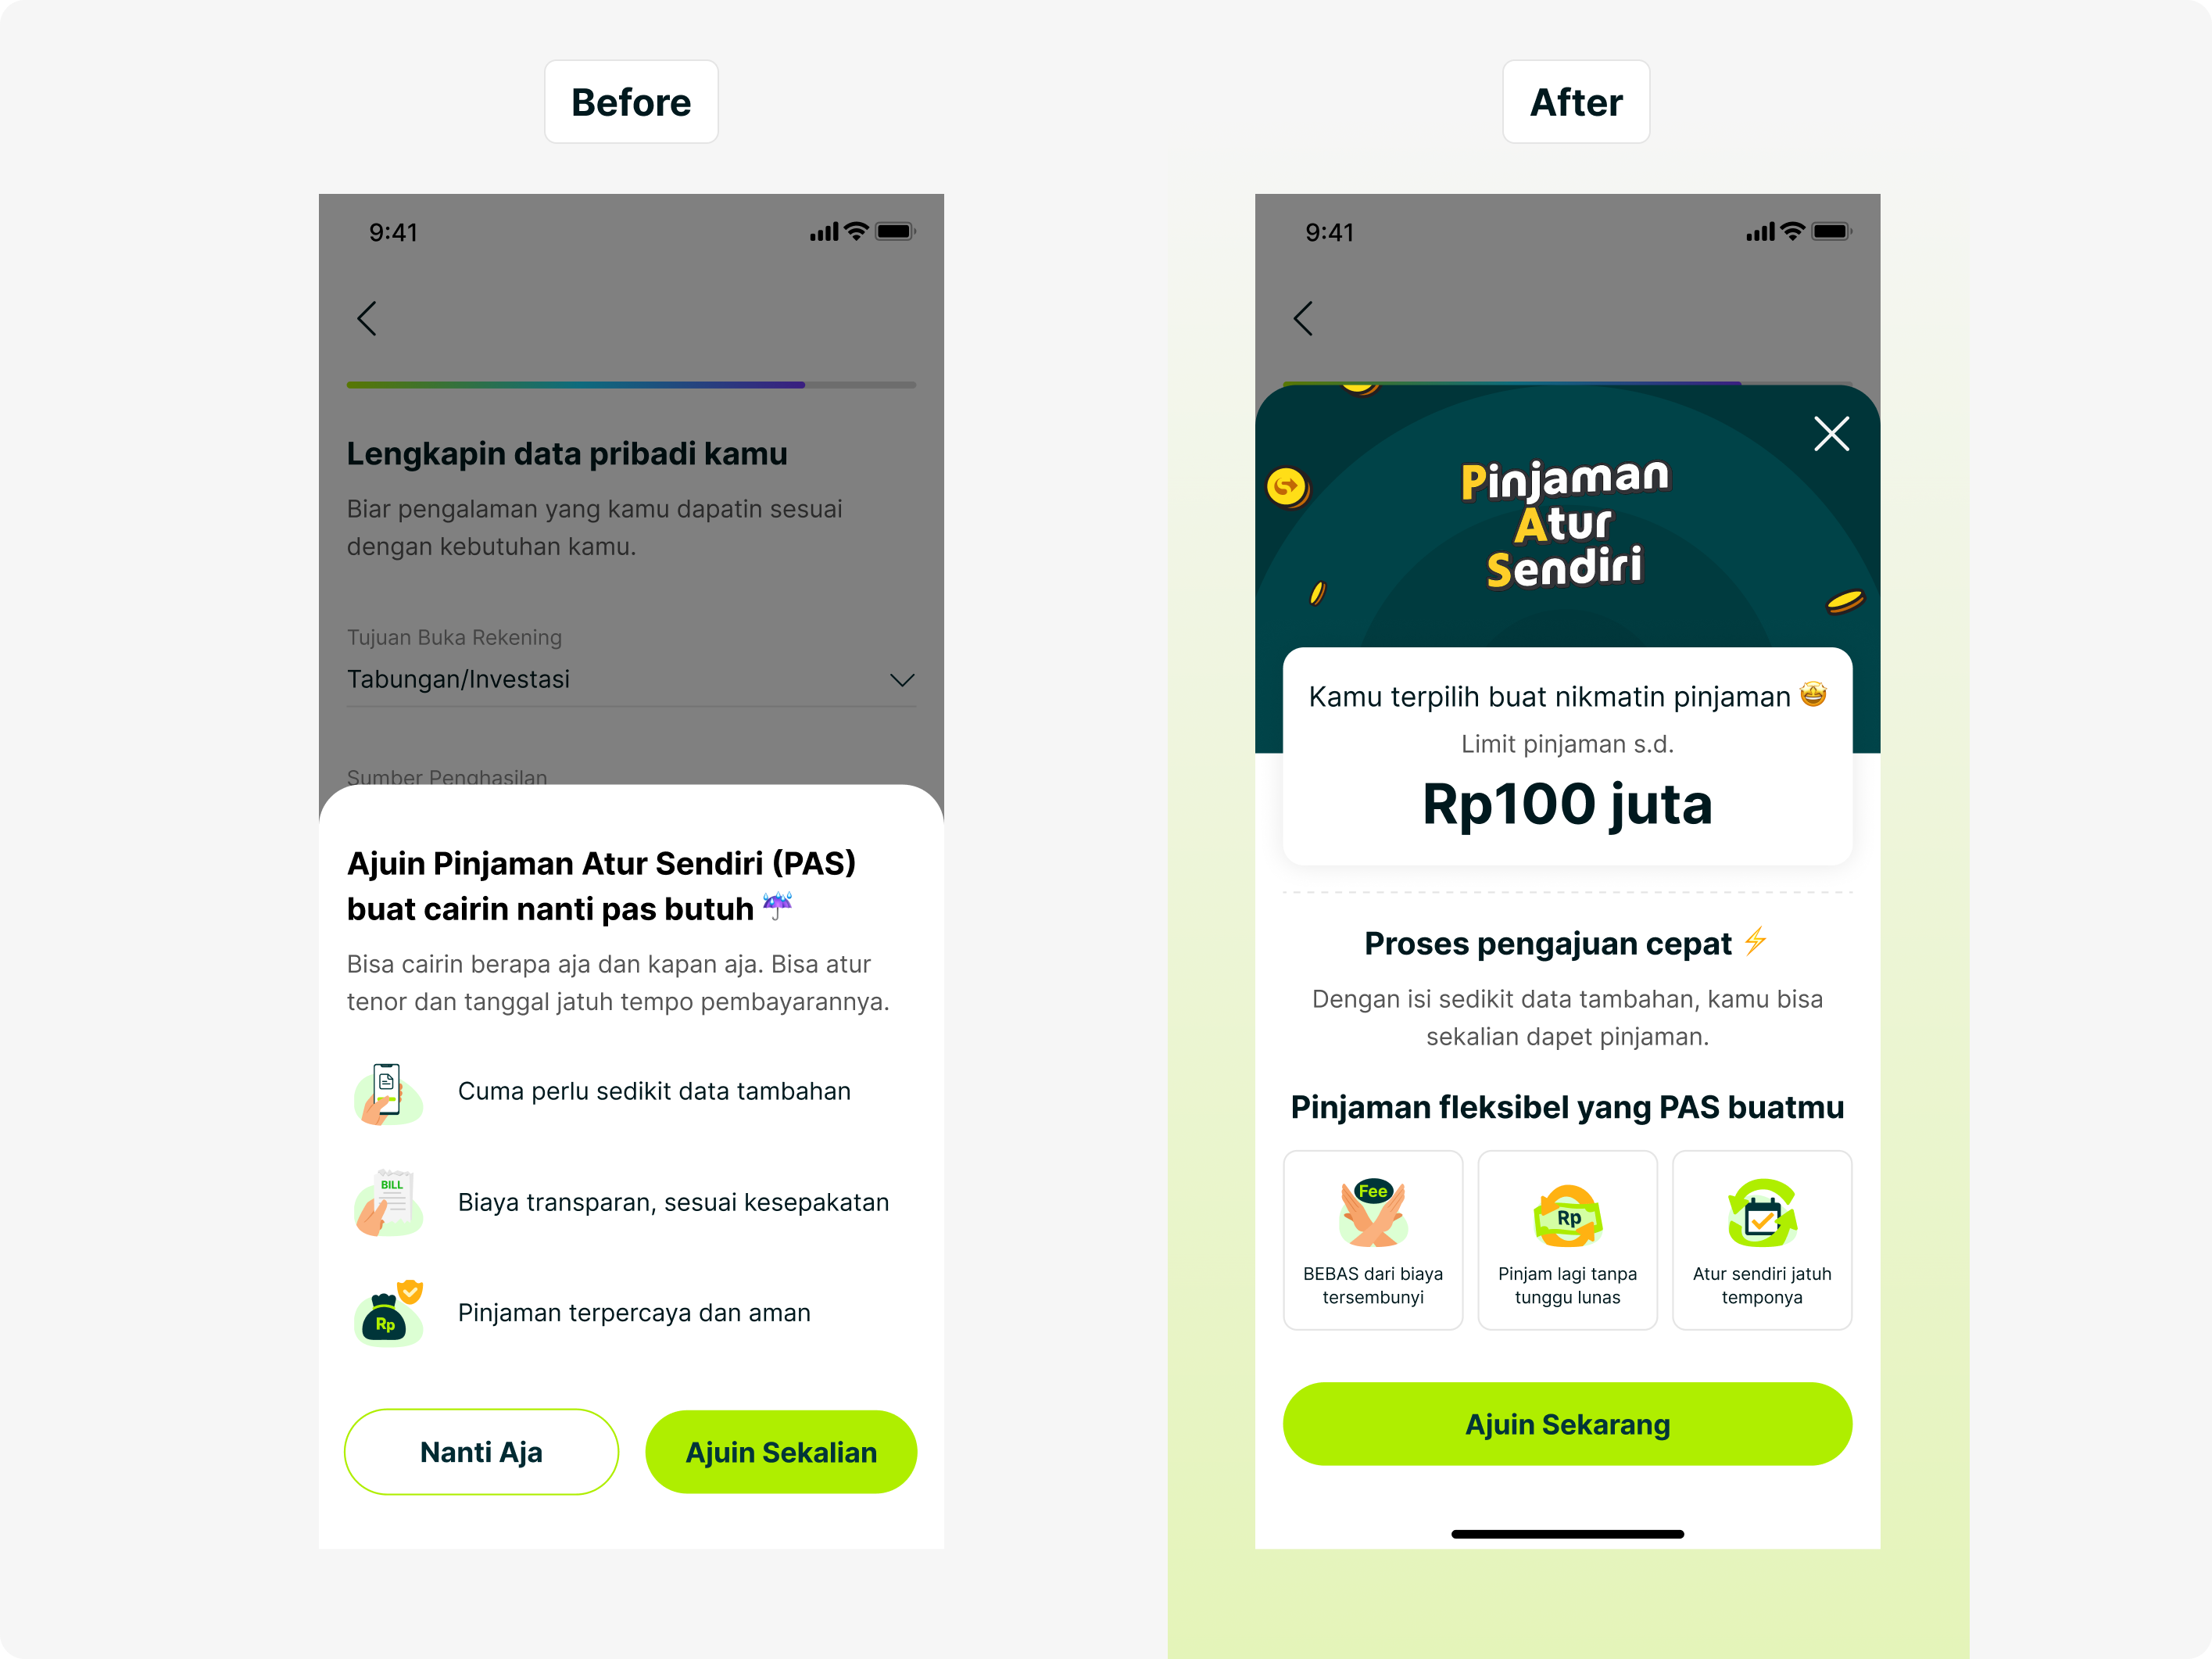
I also improved the readability of the customer value proposition (CVP). The previous layout was difficult to scale, so I reorganized the benefits into a clearer structure that could accommodate more offers.
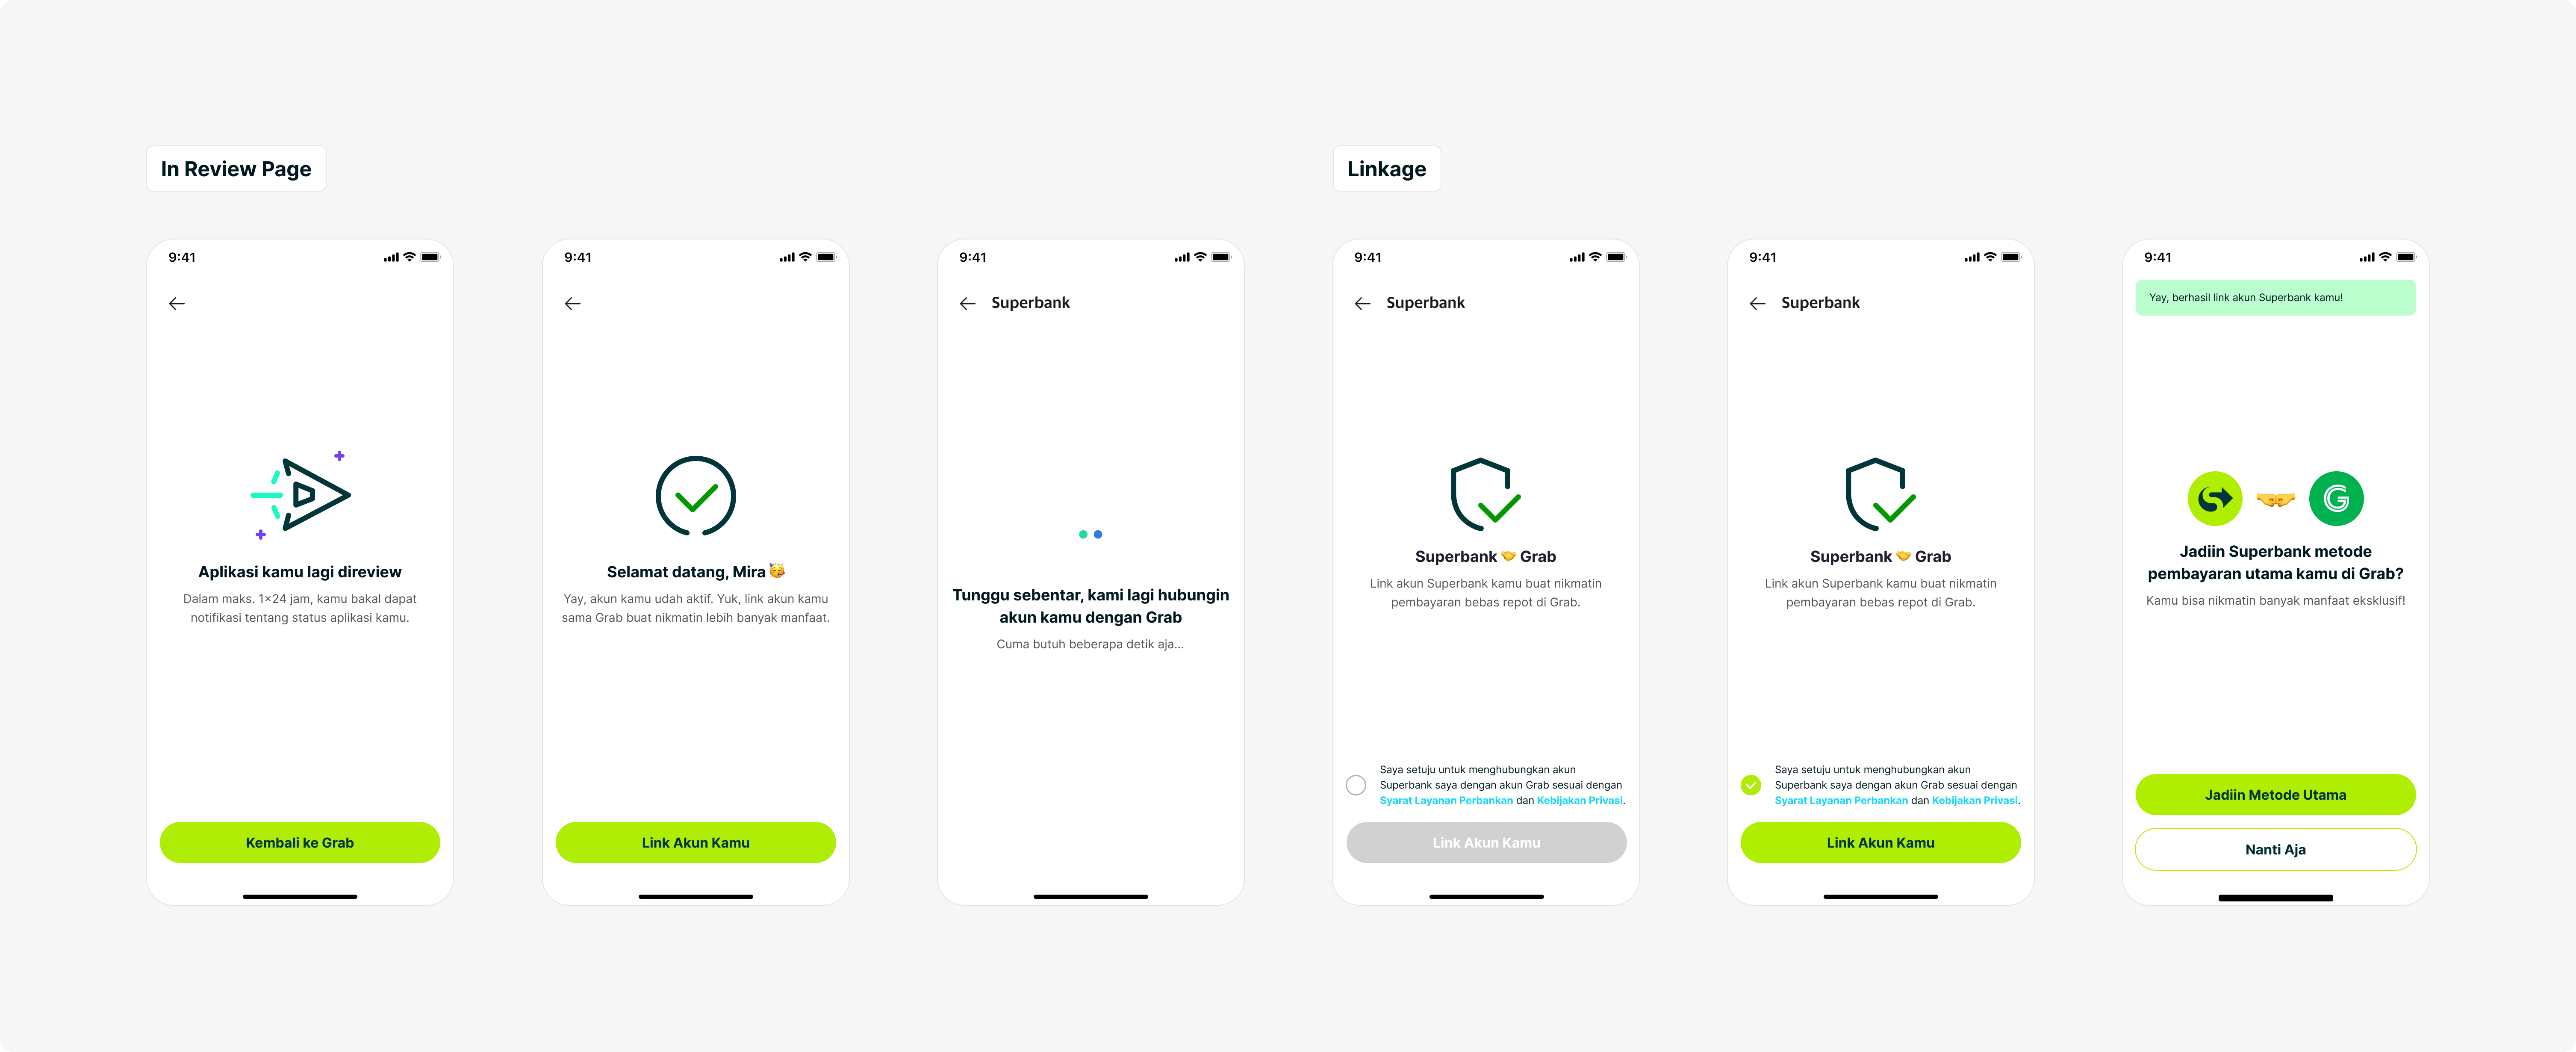
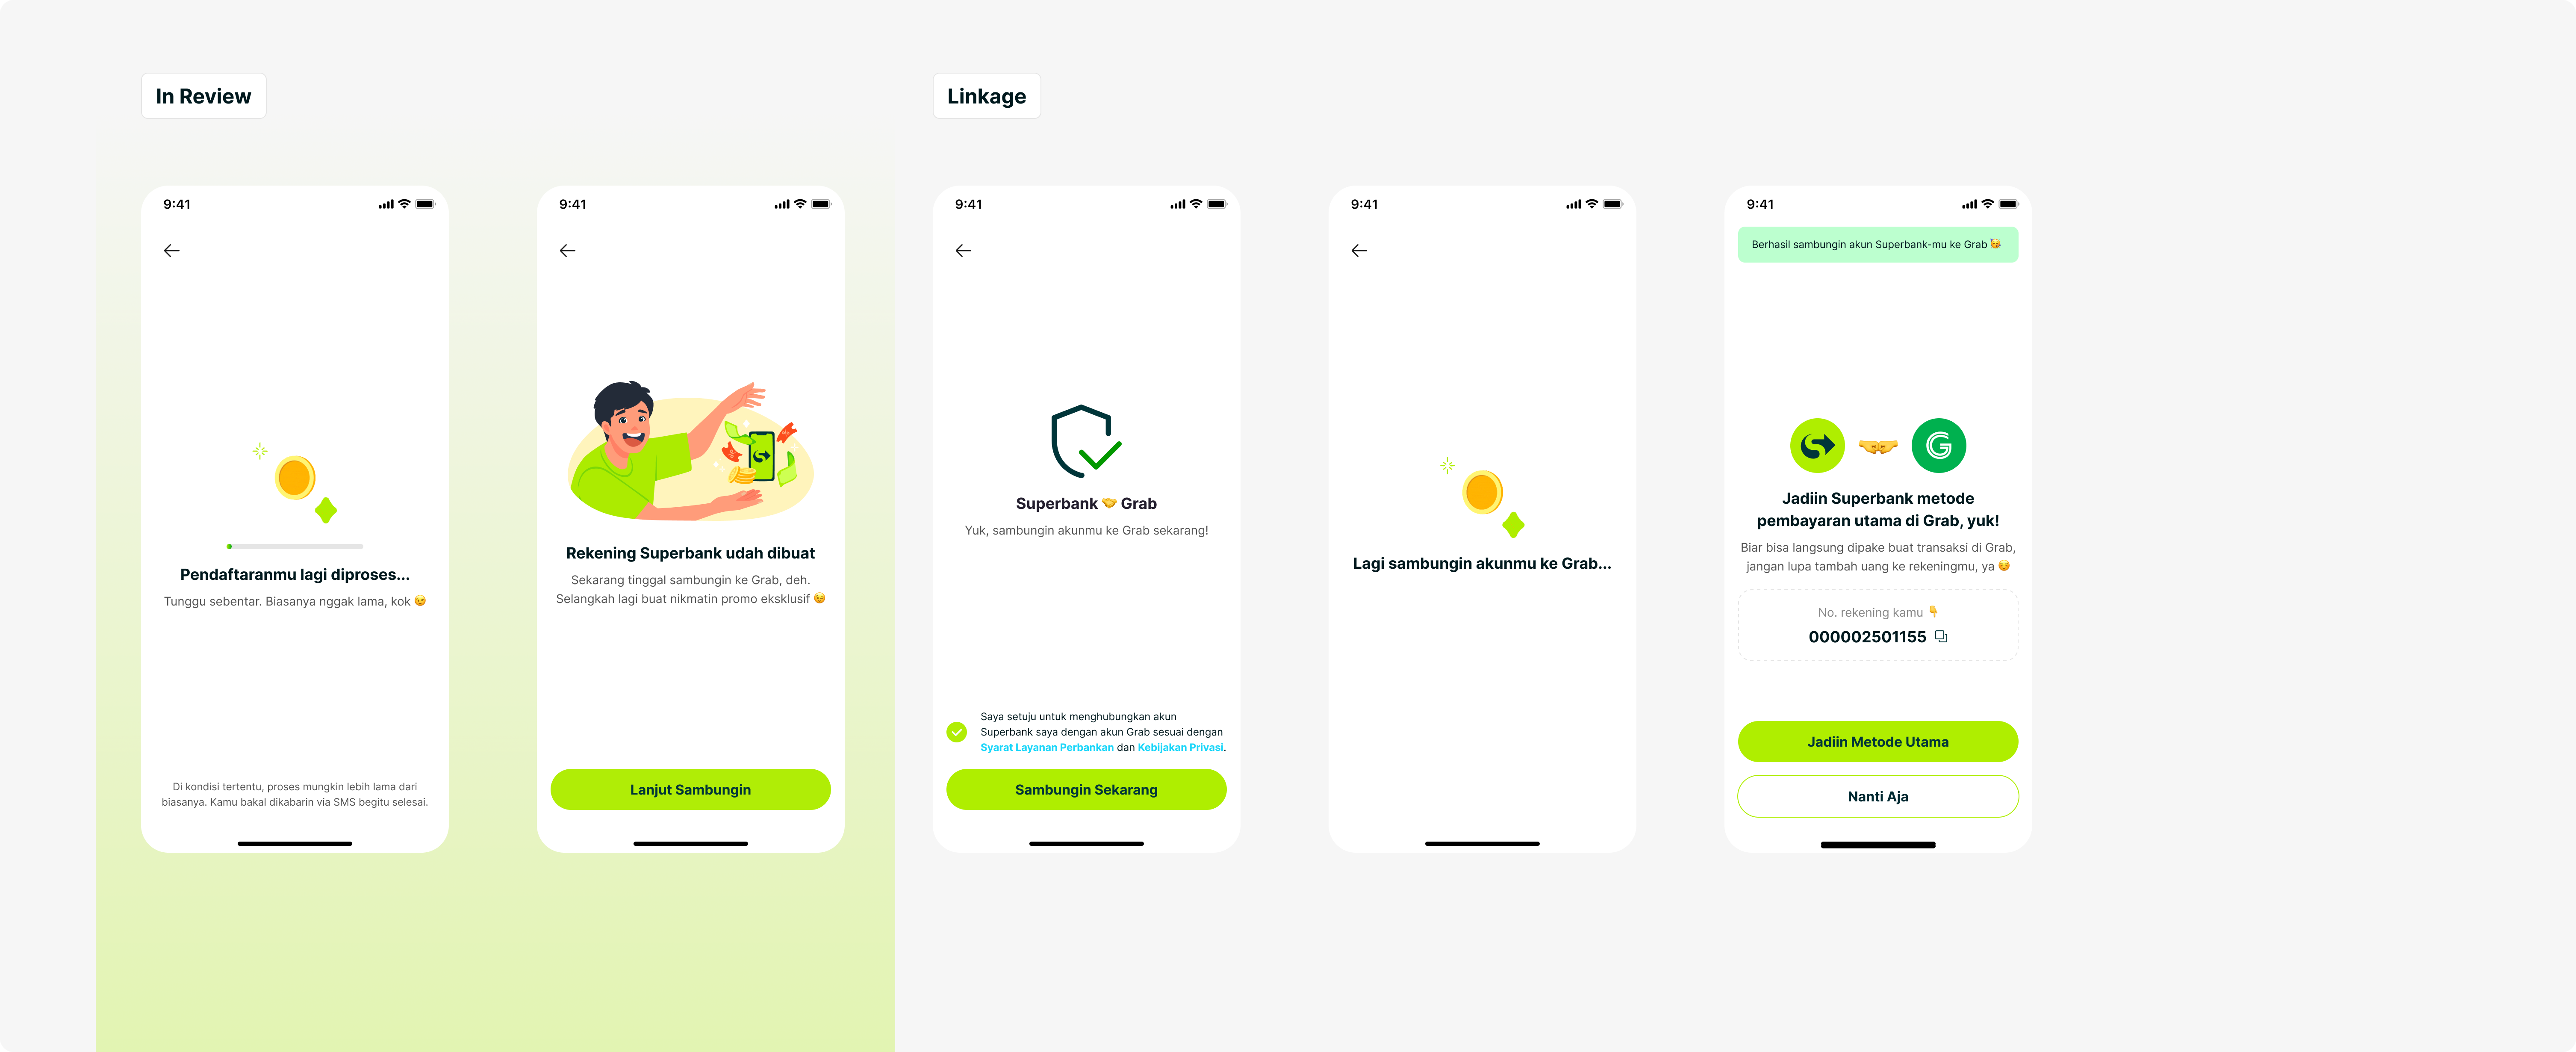
Making account creation and linking clearer
The problem. Many customers left before their account was created. The journey needed more context about what was happening and what to do next.
The change. I clarified the account creation status and the steps to connect Superbank with Grab, with the goal of helping customers continue through the journey.
Working together. I worked with UX research and copywriters to make the language more human and explain each step in terms customers could understand.
Impact
35%
Reduction in account-linking drop-off.
Making Borrowing More Accessible
As Superbank grew, lending became an important revenue driver. But making loans available wasn't enough. We also needed to help customers discover and access them at the right moment.
I worked on several acquisition and discovery initiatives for Pinjaman Atur Sendiri (PAS), both within Superbank and through embedded experiences in Grab and OVO.
Lending Acquisition: Finding Borrowing Intent Earlier
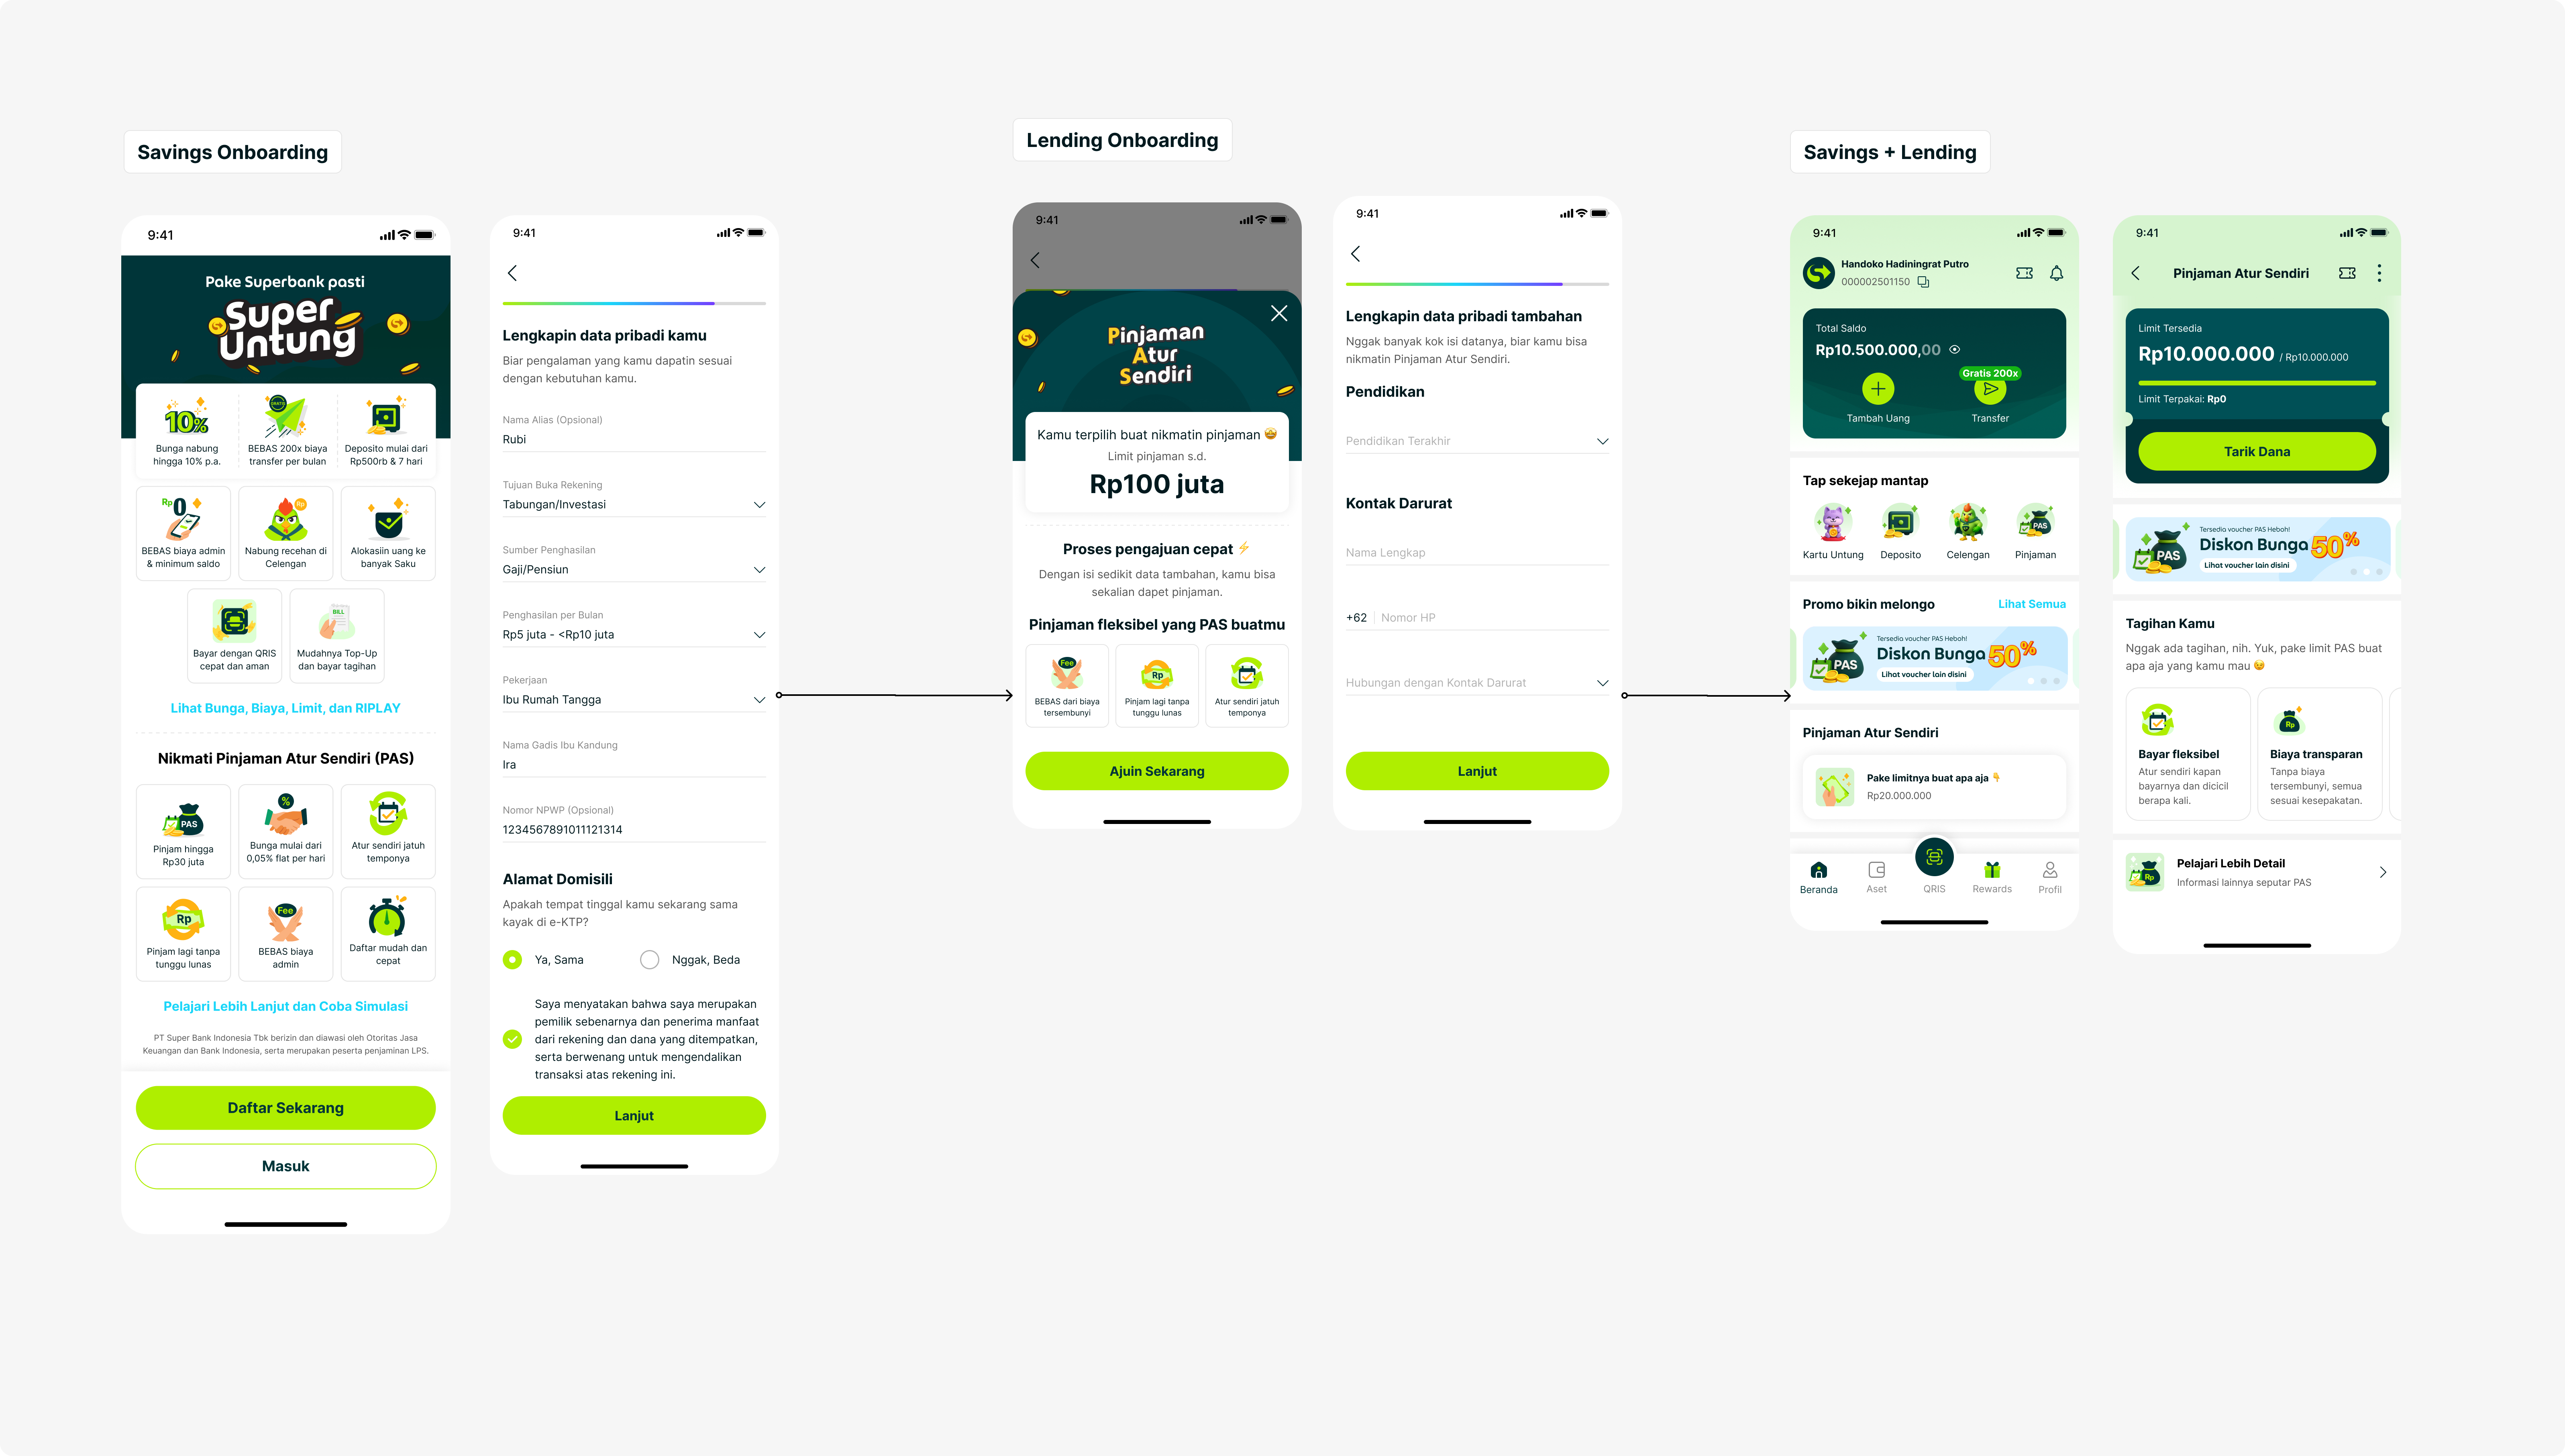
The conventional journey required customers to open a bank account before discovering lending products. But not everyone comes to a bank looking for a savings account. Some are there because they need to borrow.
This led us to explore a different approach: allowing customers to express their borrowing intent earlier in onboarding.
I led the exploration of lending opt-ins, experimenting with placements, messaging, and entry points through A/B/C testing to understand how we could better connect interested customers with PAS.
Impact
XX%
Loan acquisition conversion.
Embedded Lending: Bringing Loans Closer to Customers
Grab and OVO already had established customer relationships, creating an opportunity to introduce lending without requiring customers to begin their journey in another app.
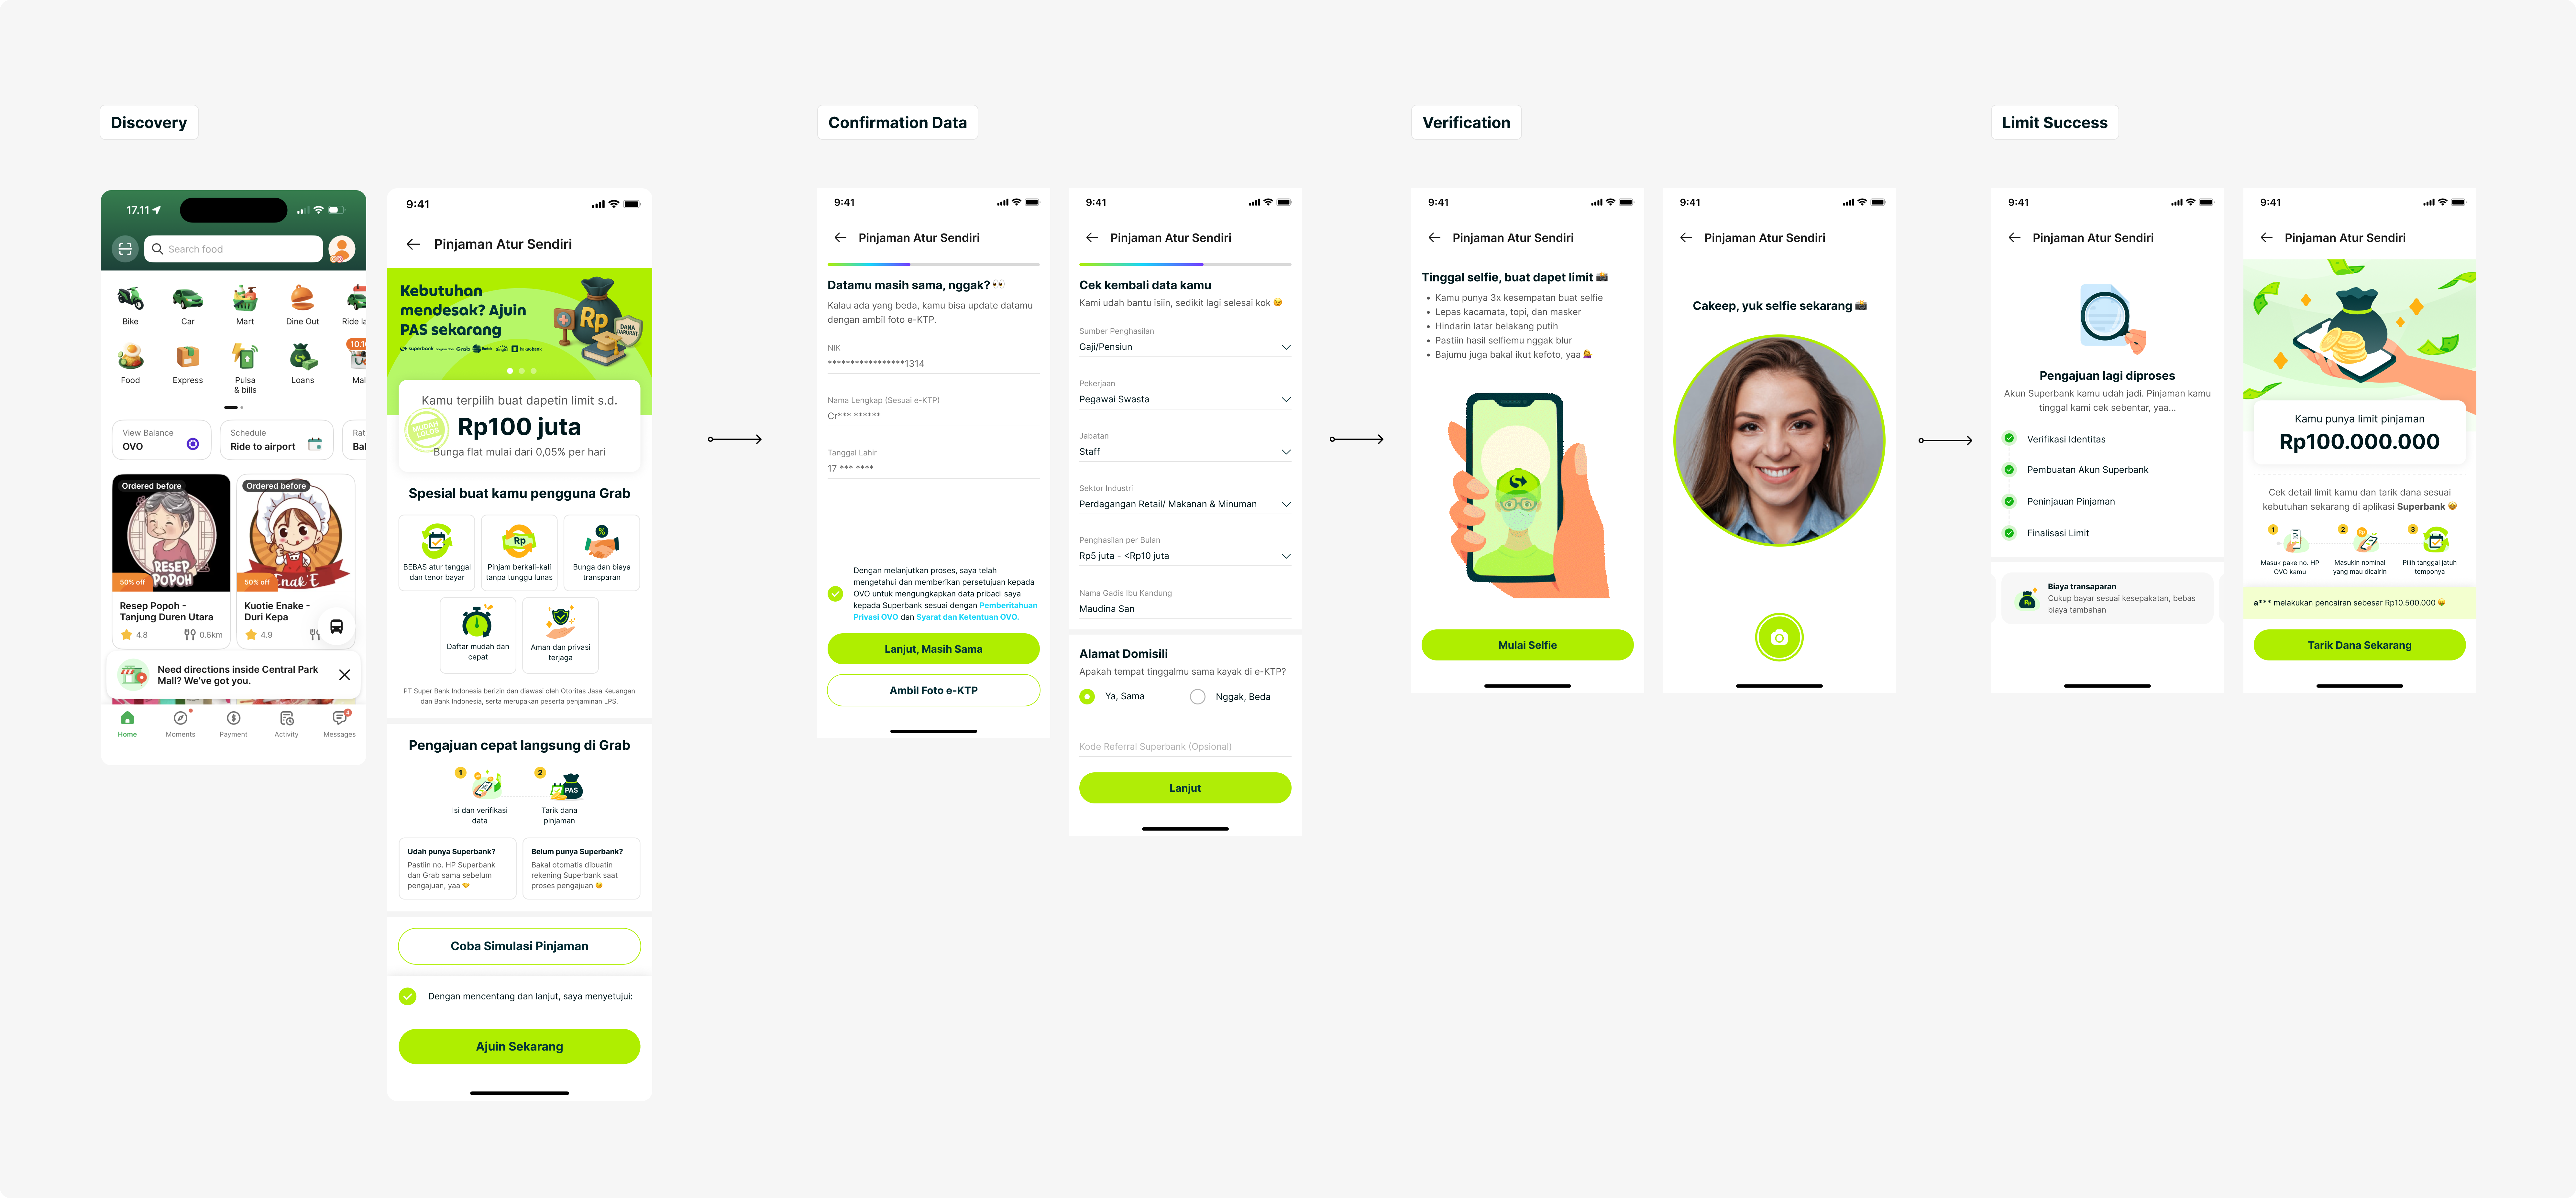
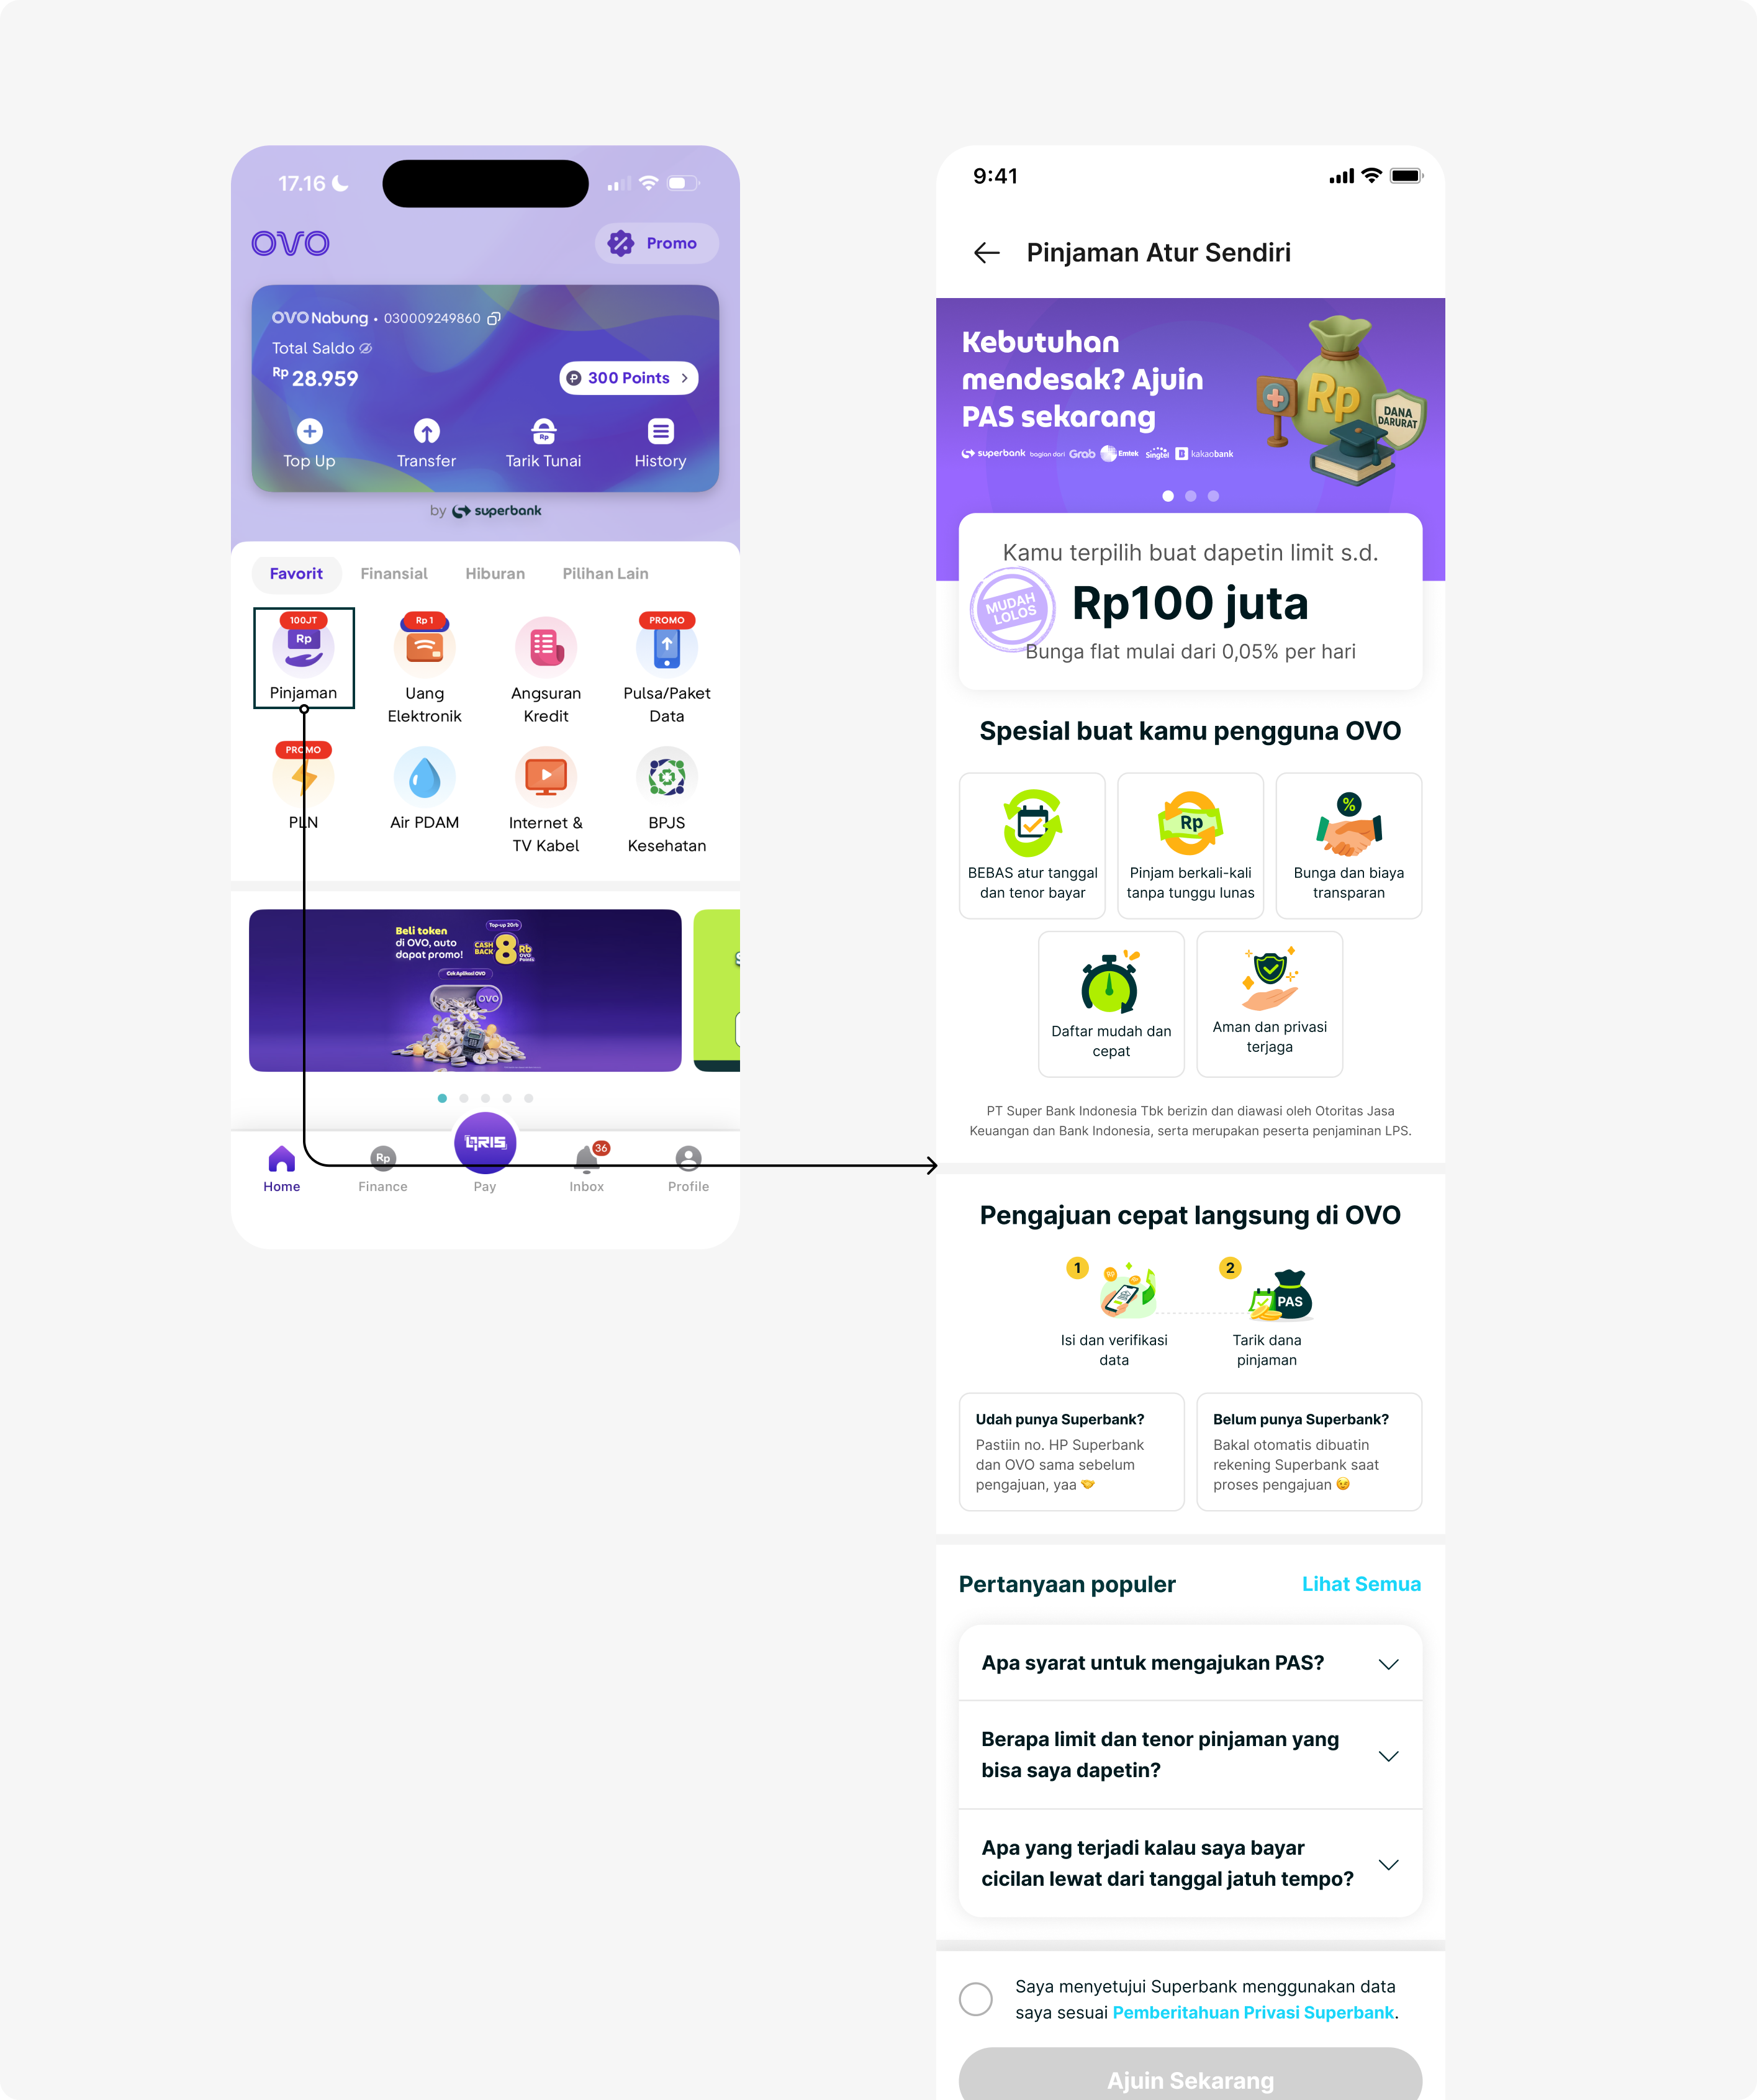
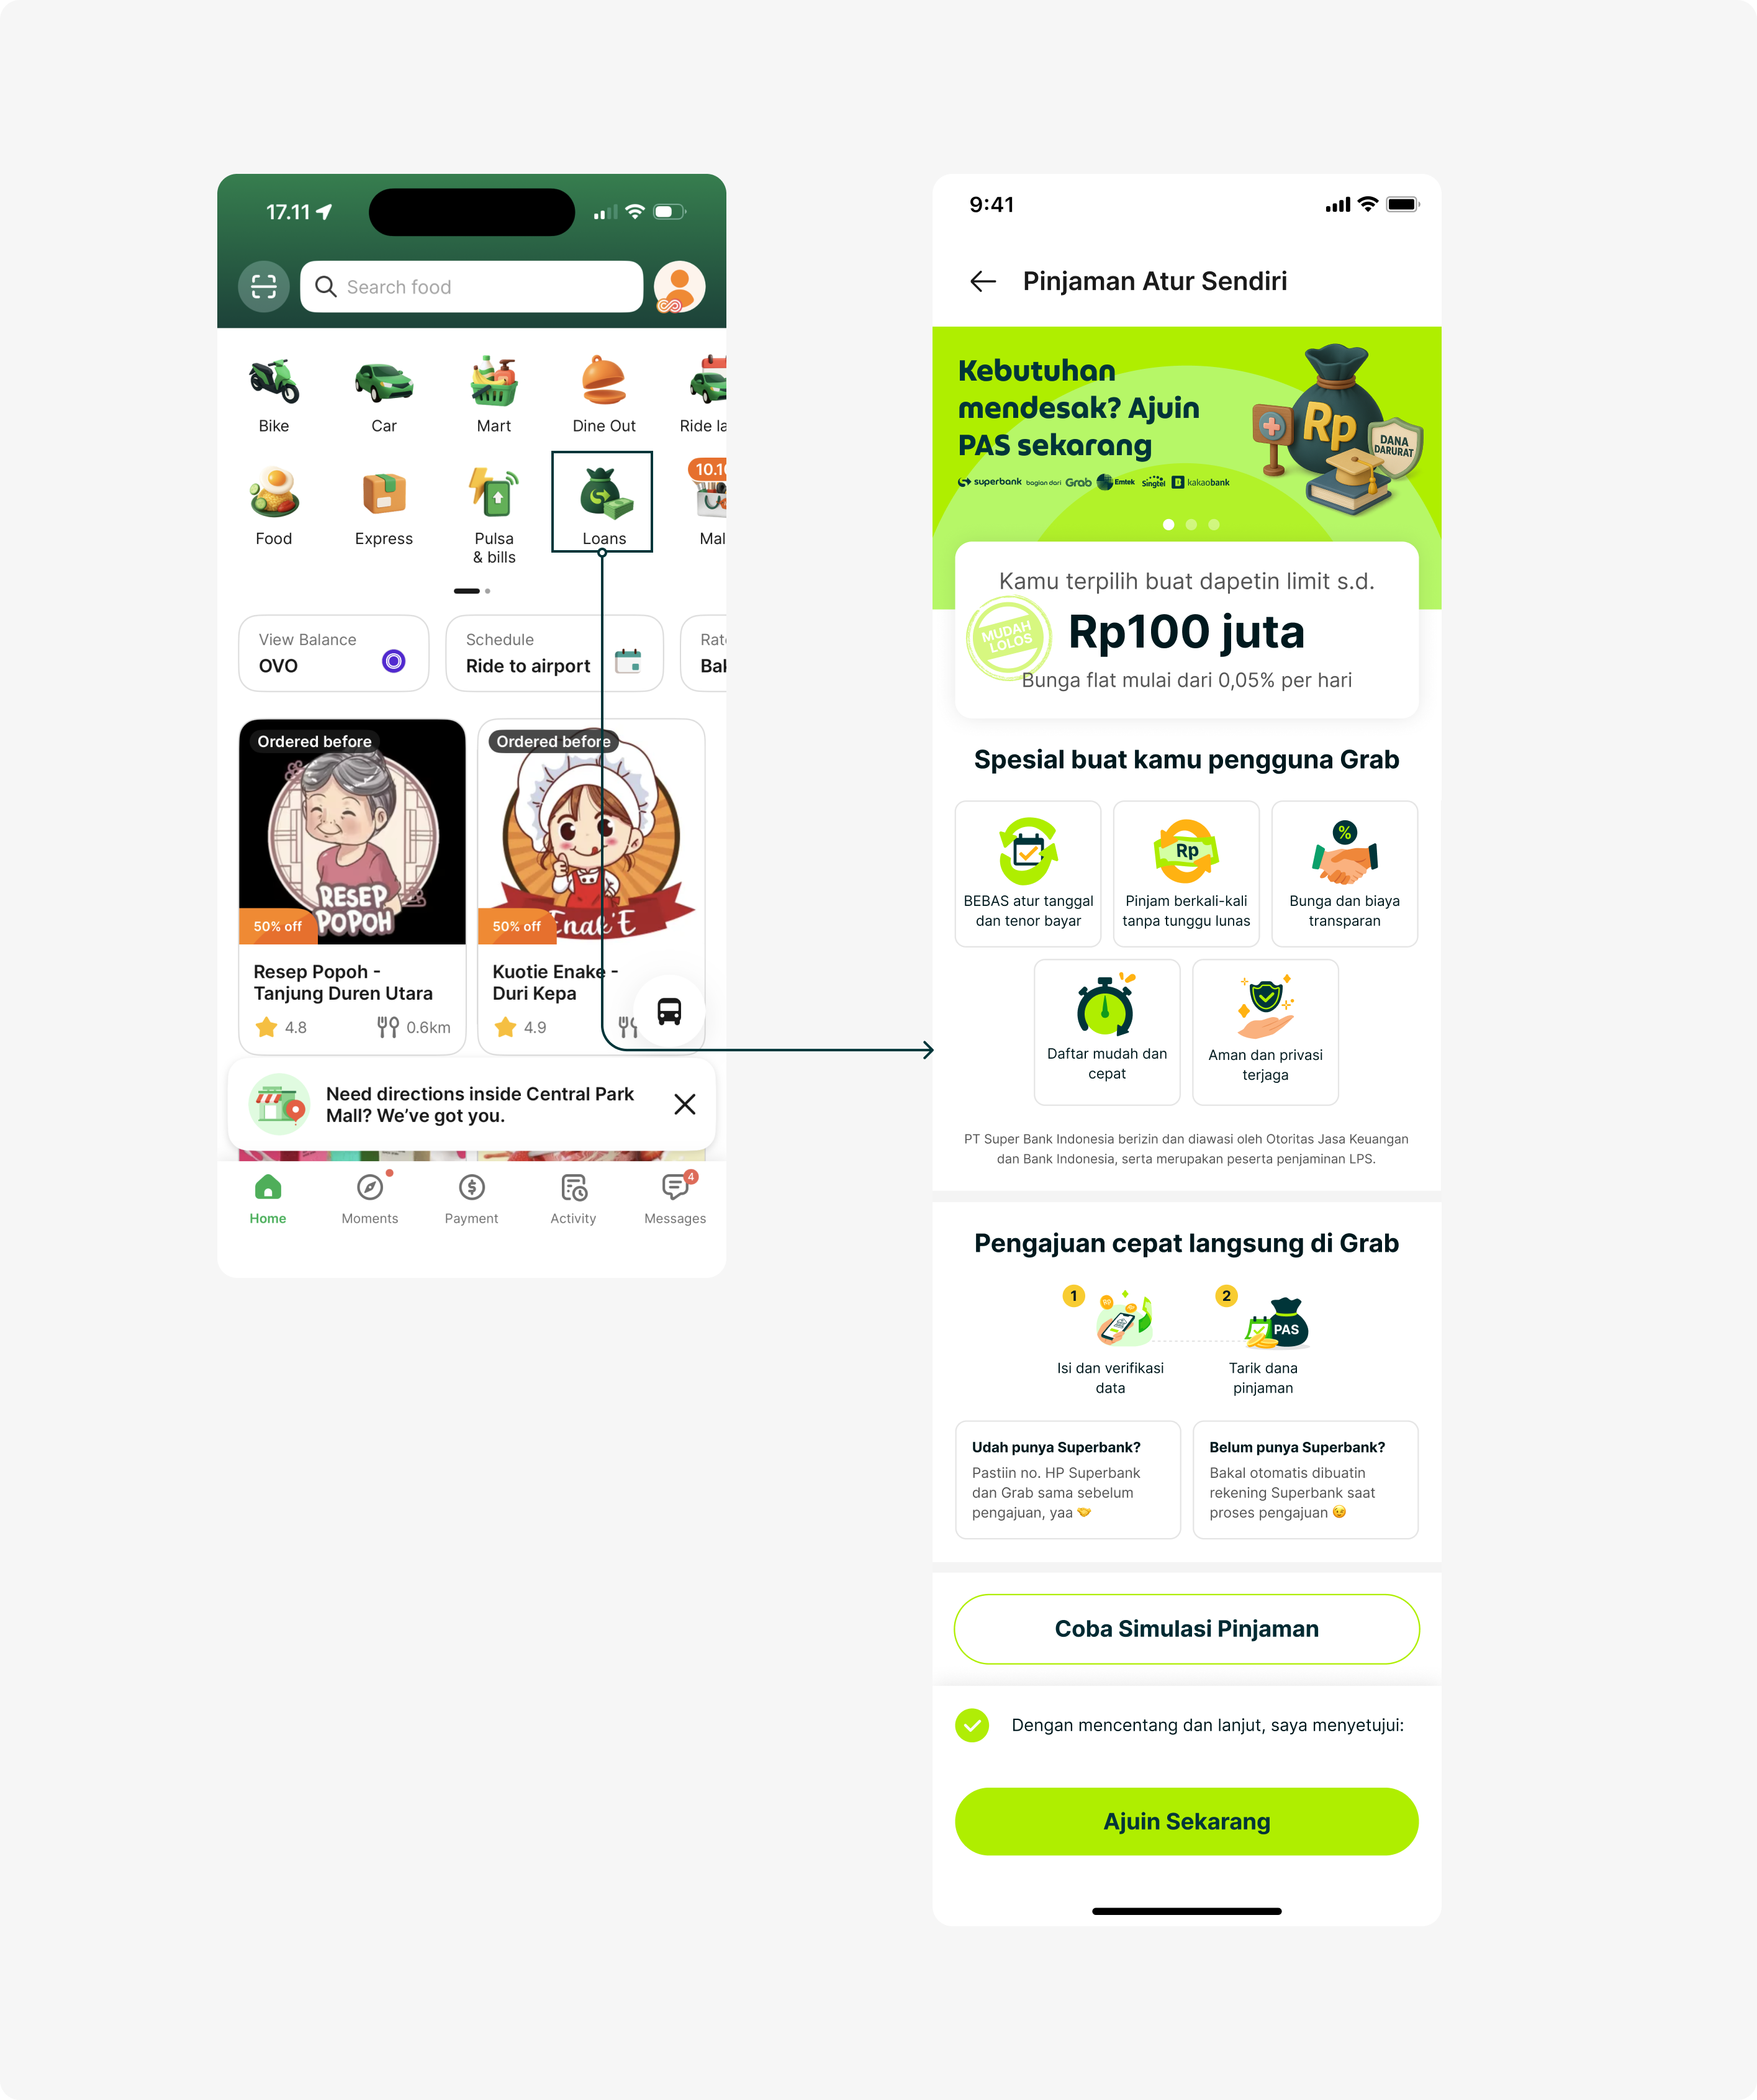
Building on our experience with embedded banking, I led design initiatives to bring loan onboarding directly into partner ecosystems.
Through research and experimentation, we explored different customer value propositions, potential loan limits, and lending offers.
One important learning stood out: the relevance of an offer matters just as much as where we place it.
Impact
XX%
Loan conversion.
Loan Channeling: Connecting Different Lending Experiences
Not every lending experience starts and ends within the same product.
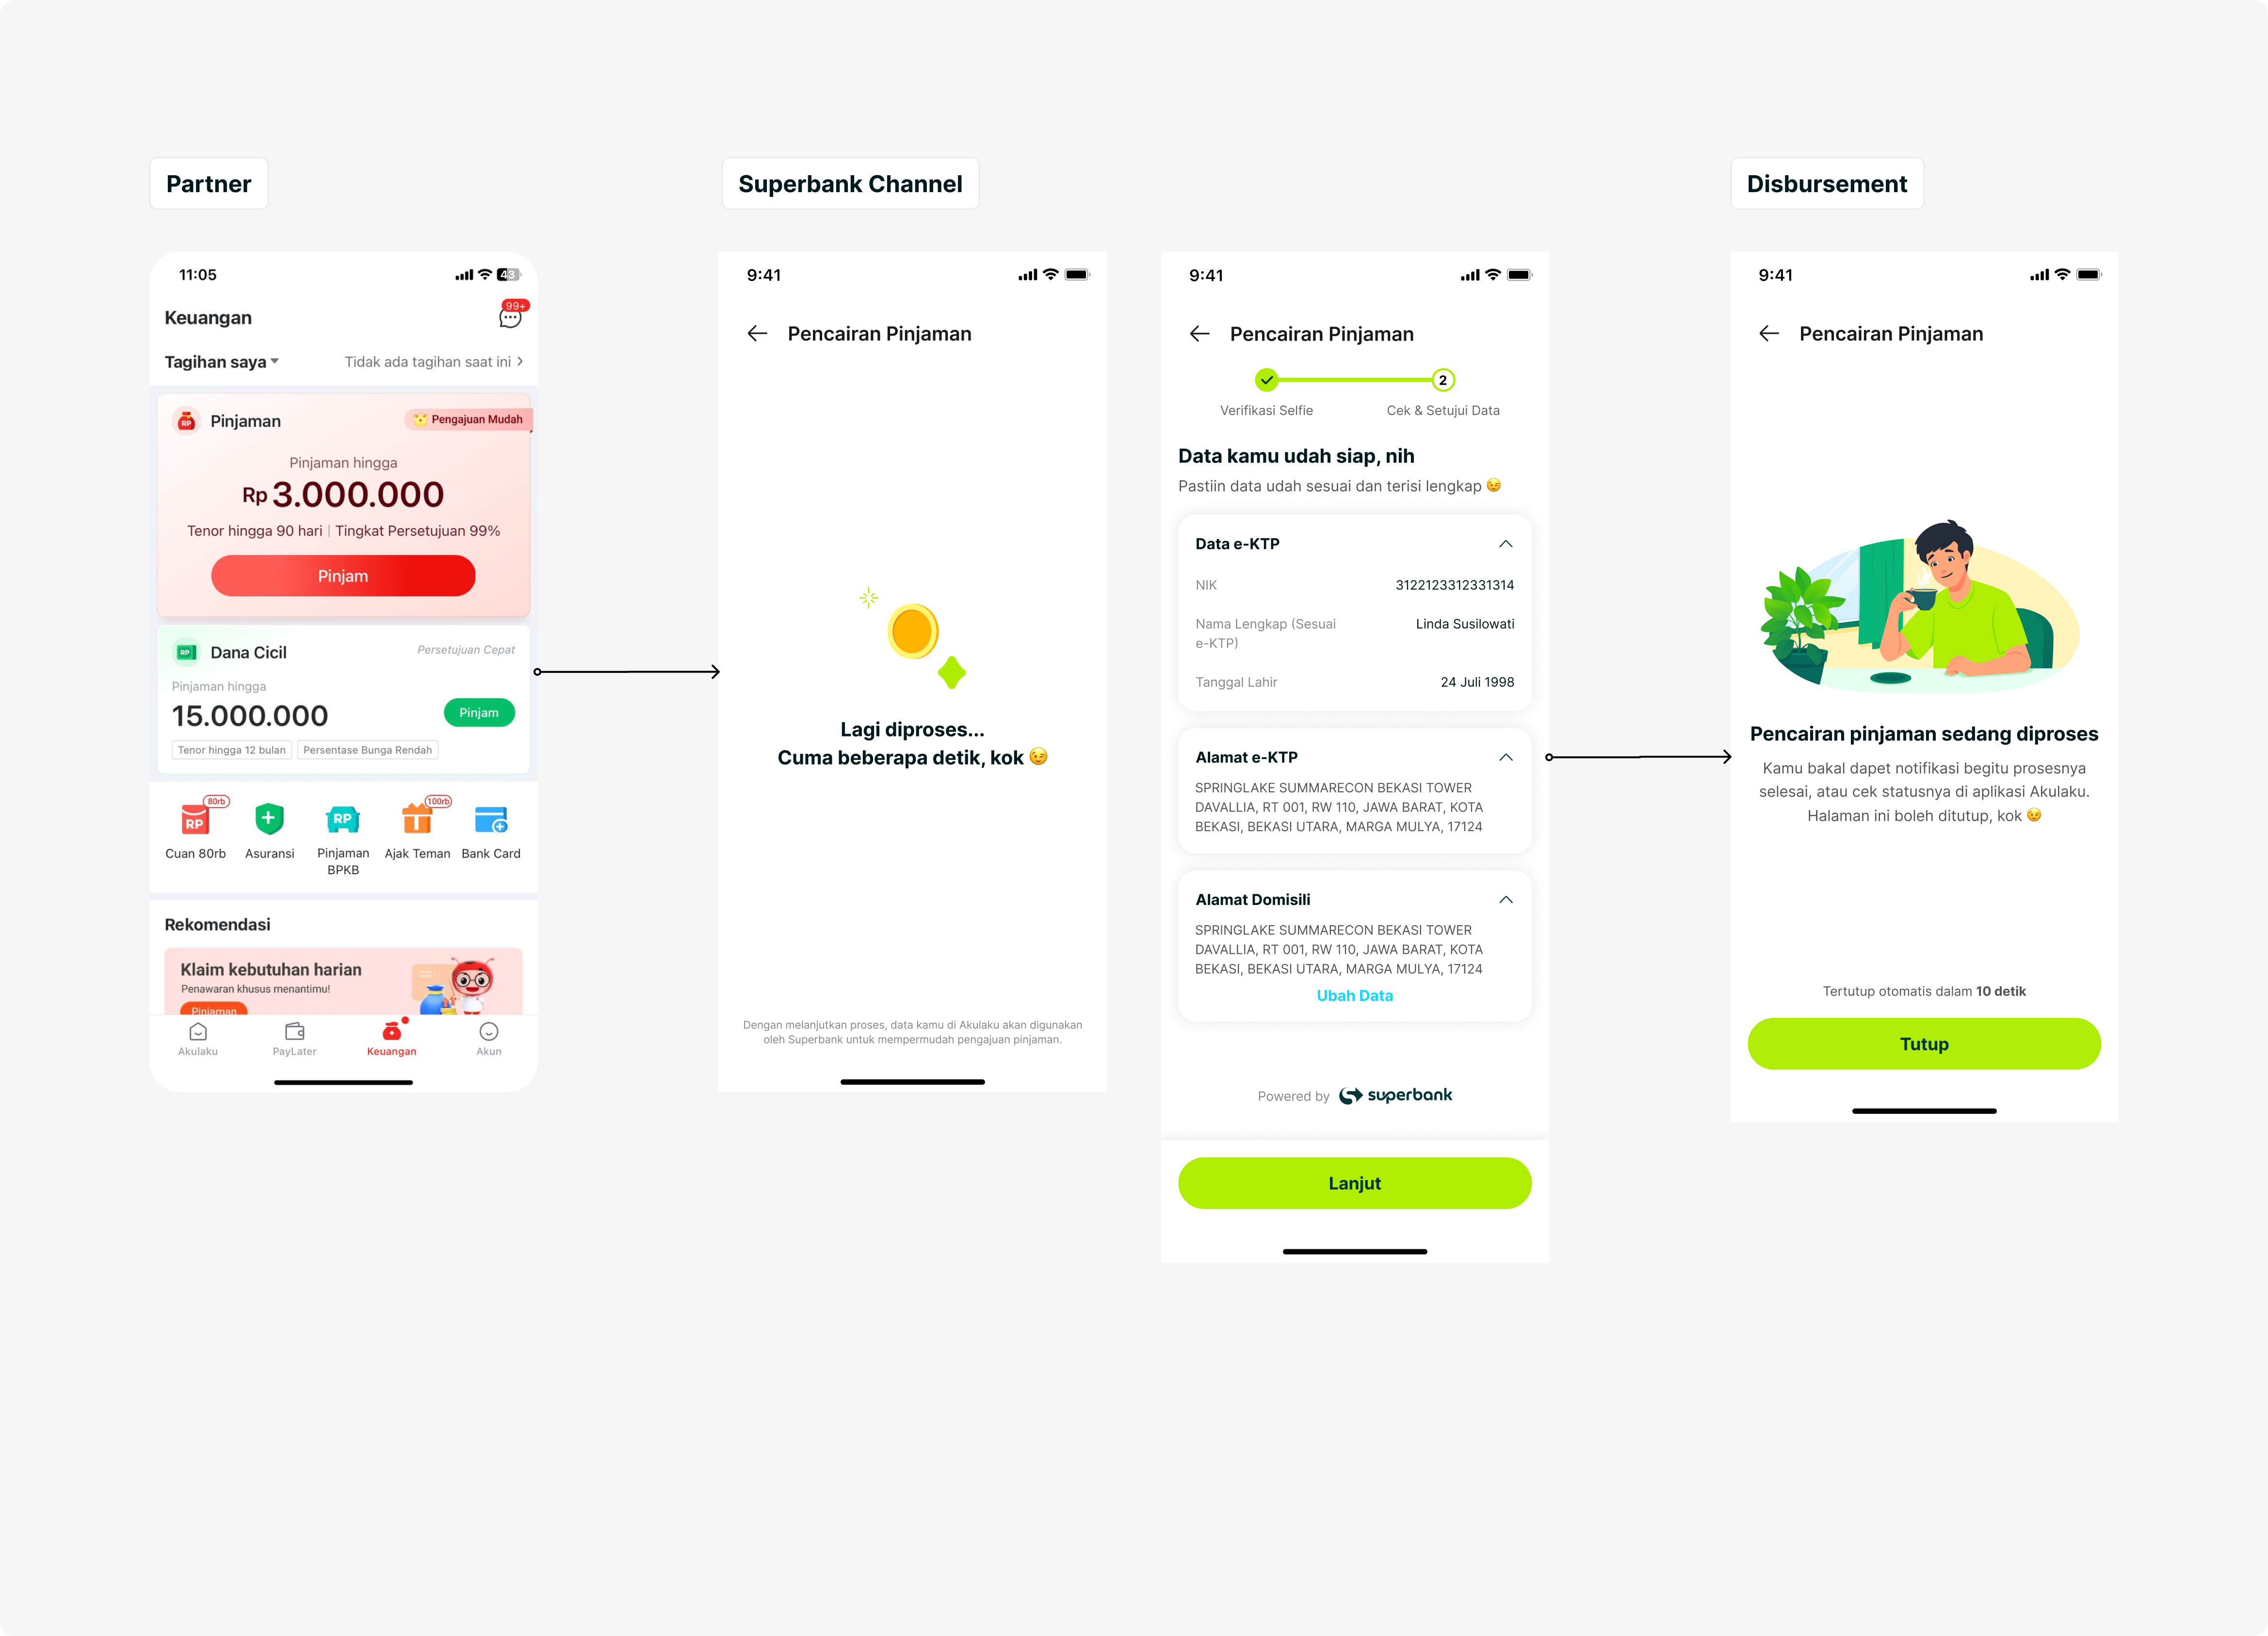
Loan channeling introduced a different challenge: creating a seamless customer journey across partners, banking systems, and different technical requirements.
I also contributed to this initiative, working through the complexity of connecting these experiences.
There's a much bigger story behind this work, one that deserves its own case study.
Everyday Banking
Acquiring customers is only the beginning. Giving them a reason to keep using the bank is another challenge.
As Superbank expanded its everyday banking capabilities, I led several payment initiatives focused on making transactions simpler, more flexible, and scalable.
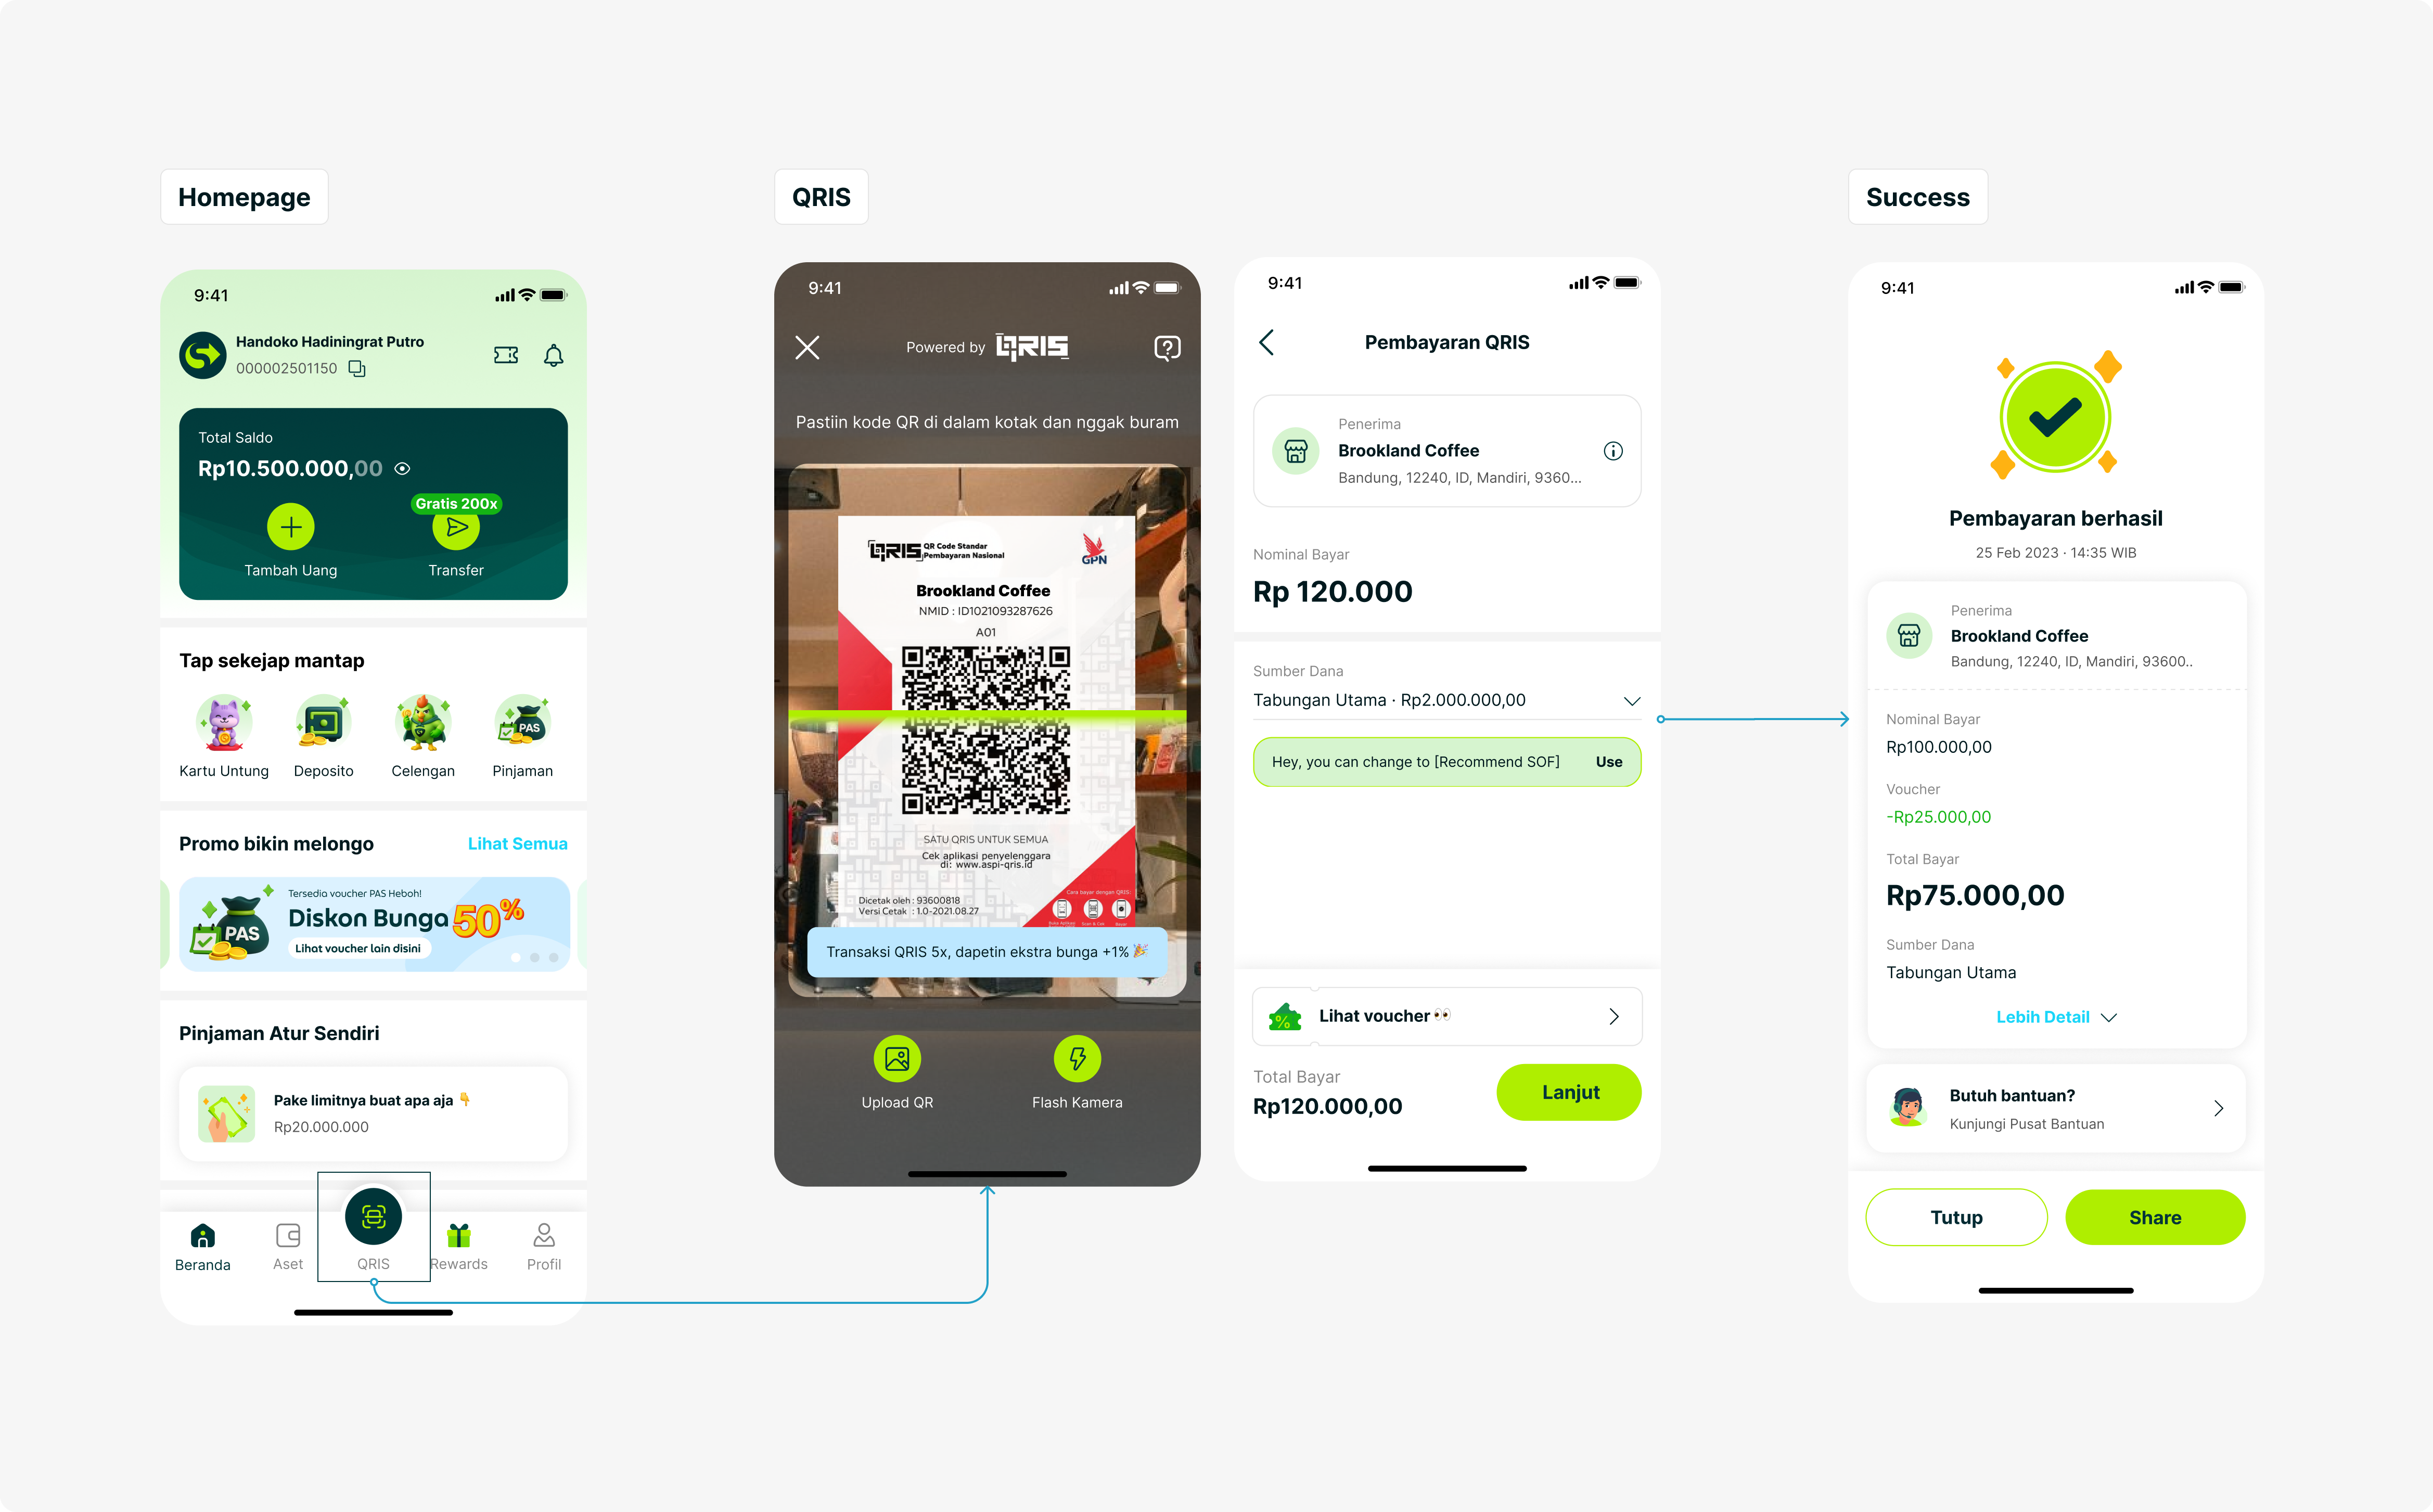
QRIS Payments: Making Everyday Payments More Flexible
QRIS had become an important part of everyday transactions in Indonesia, making it a critical payment capability for Superbank.
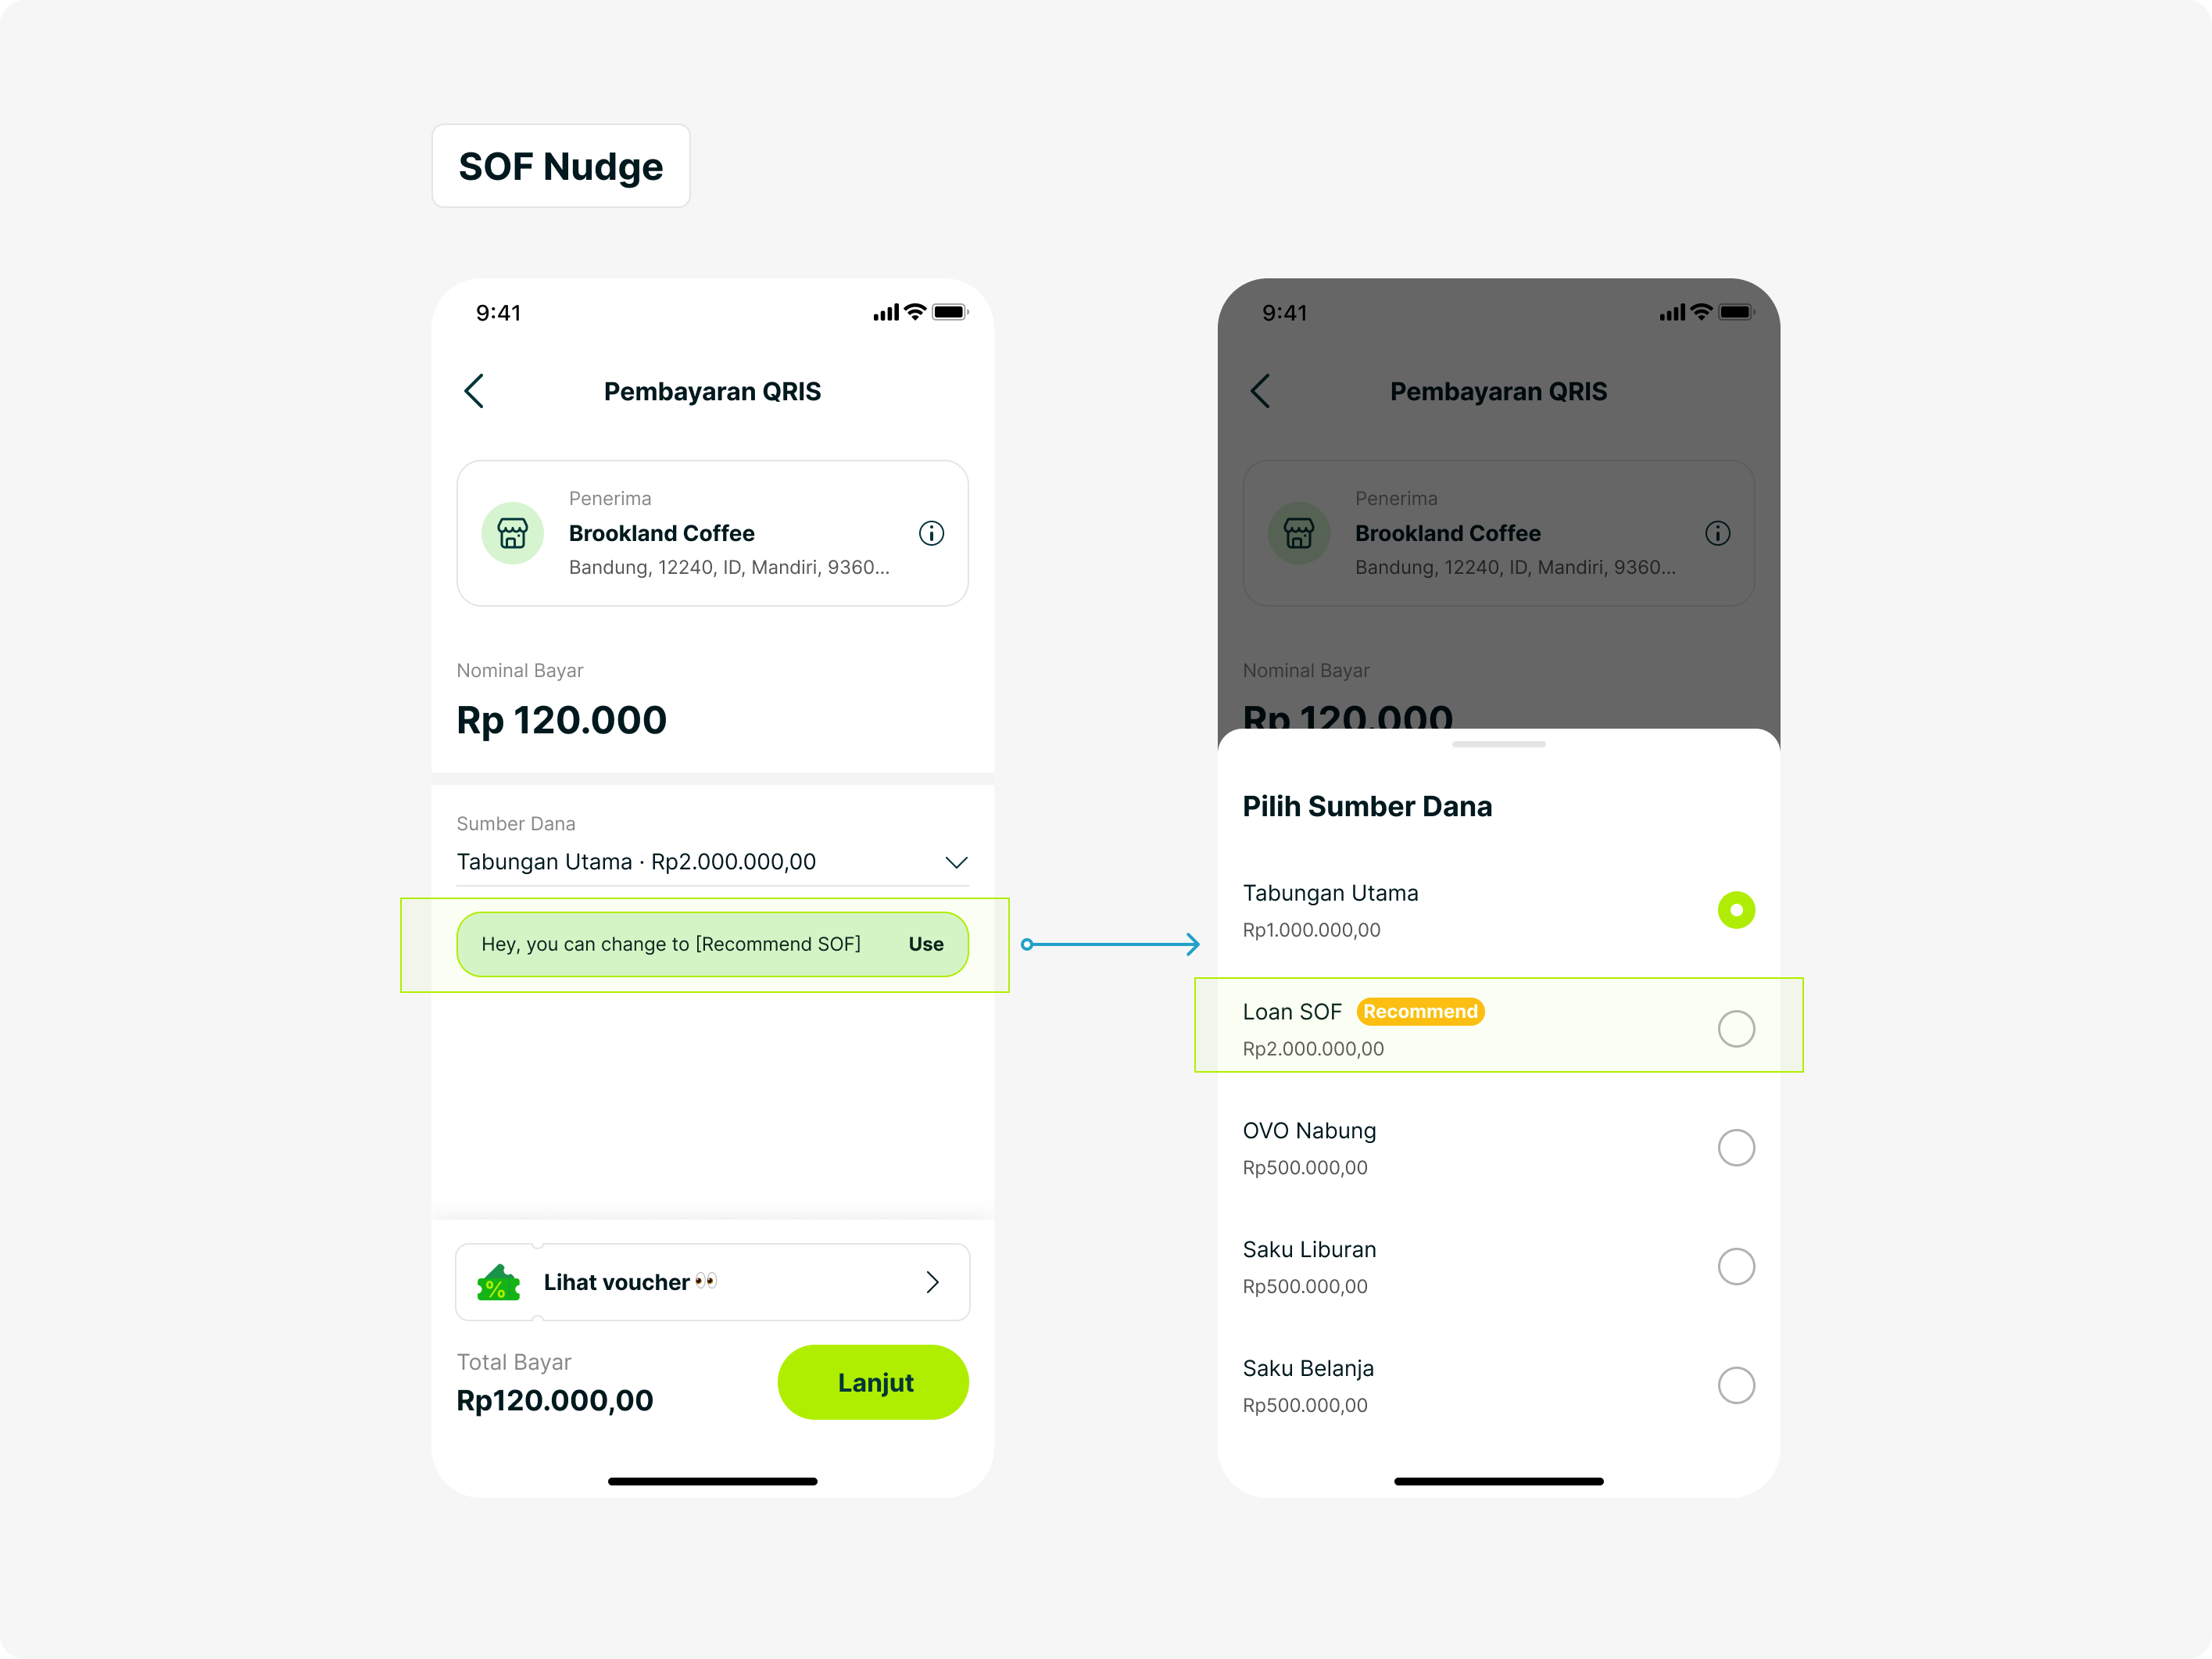
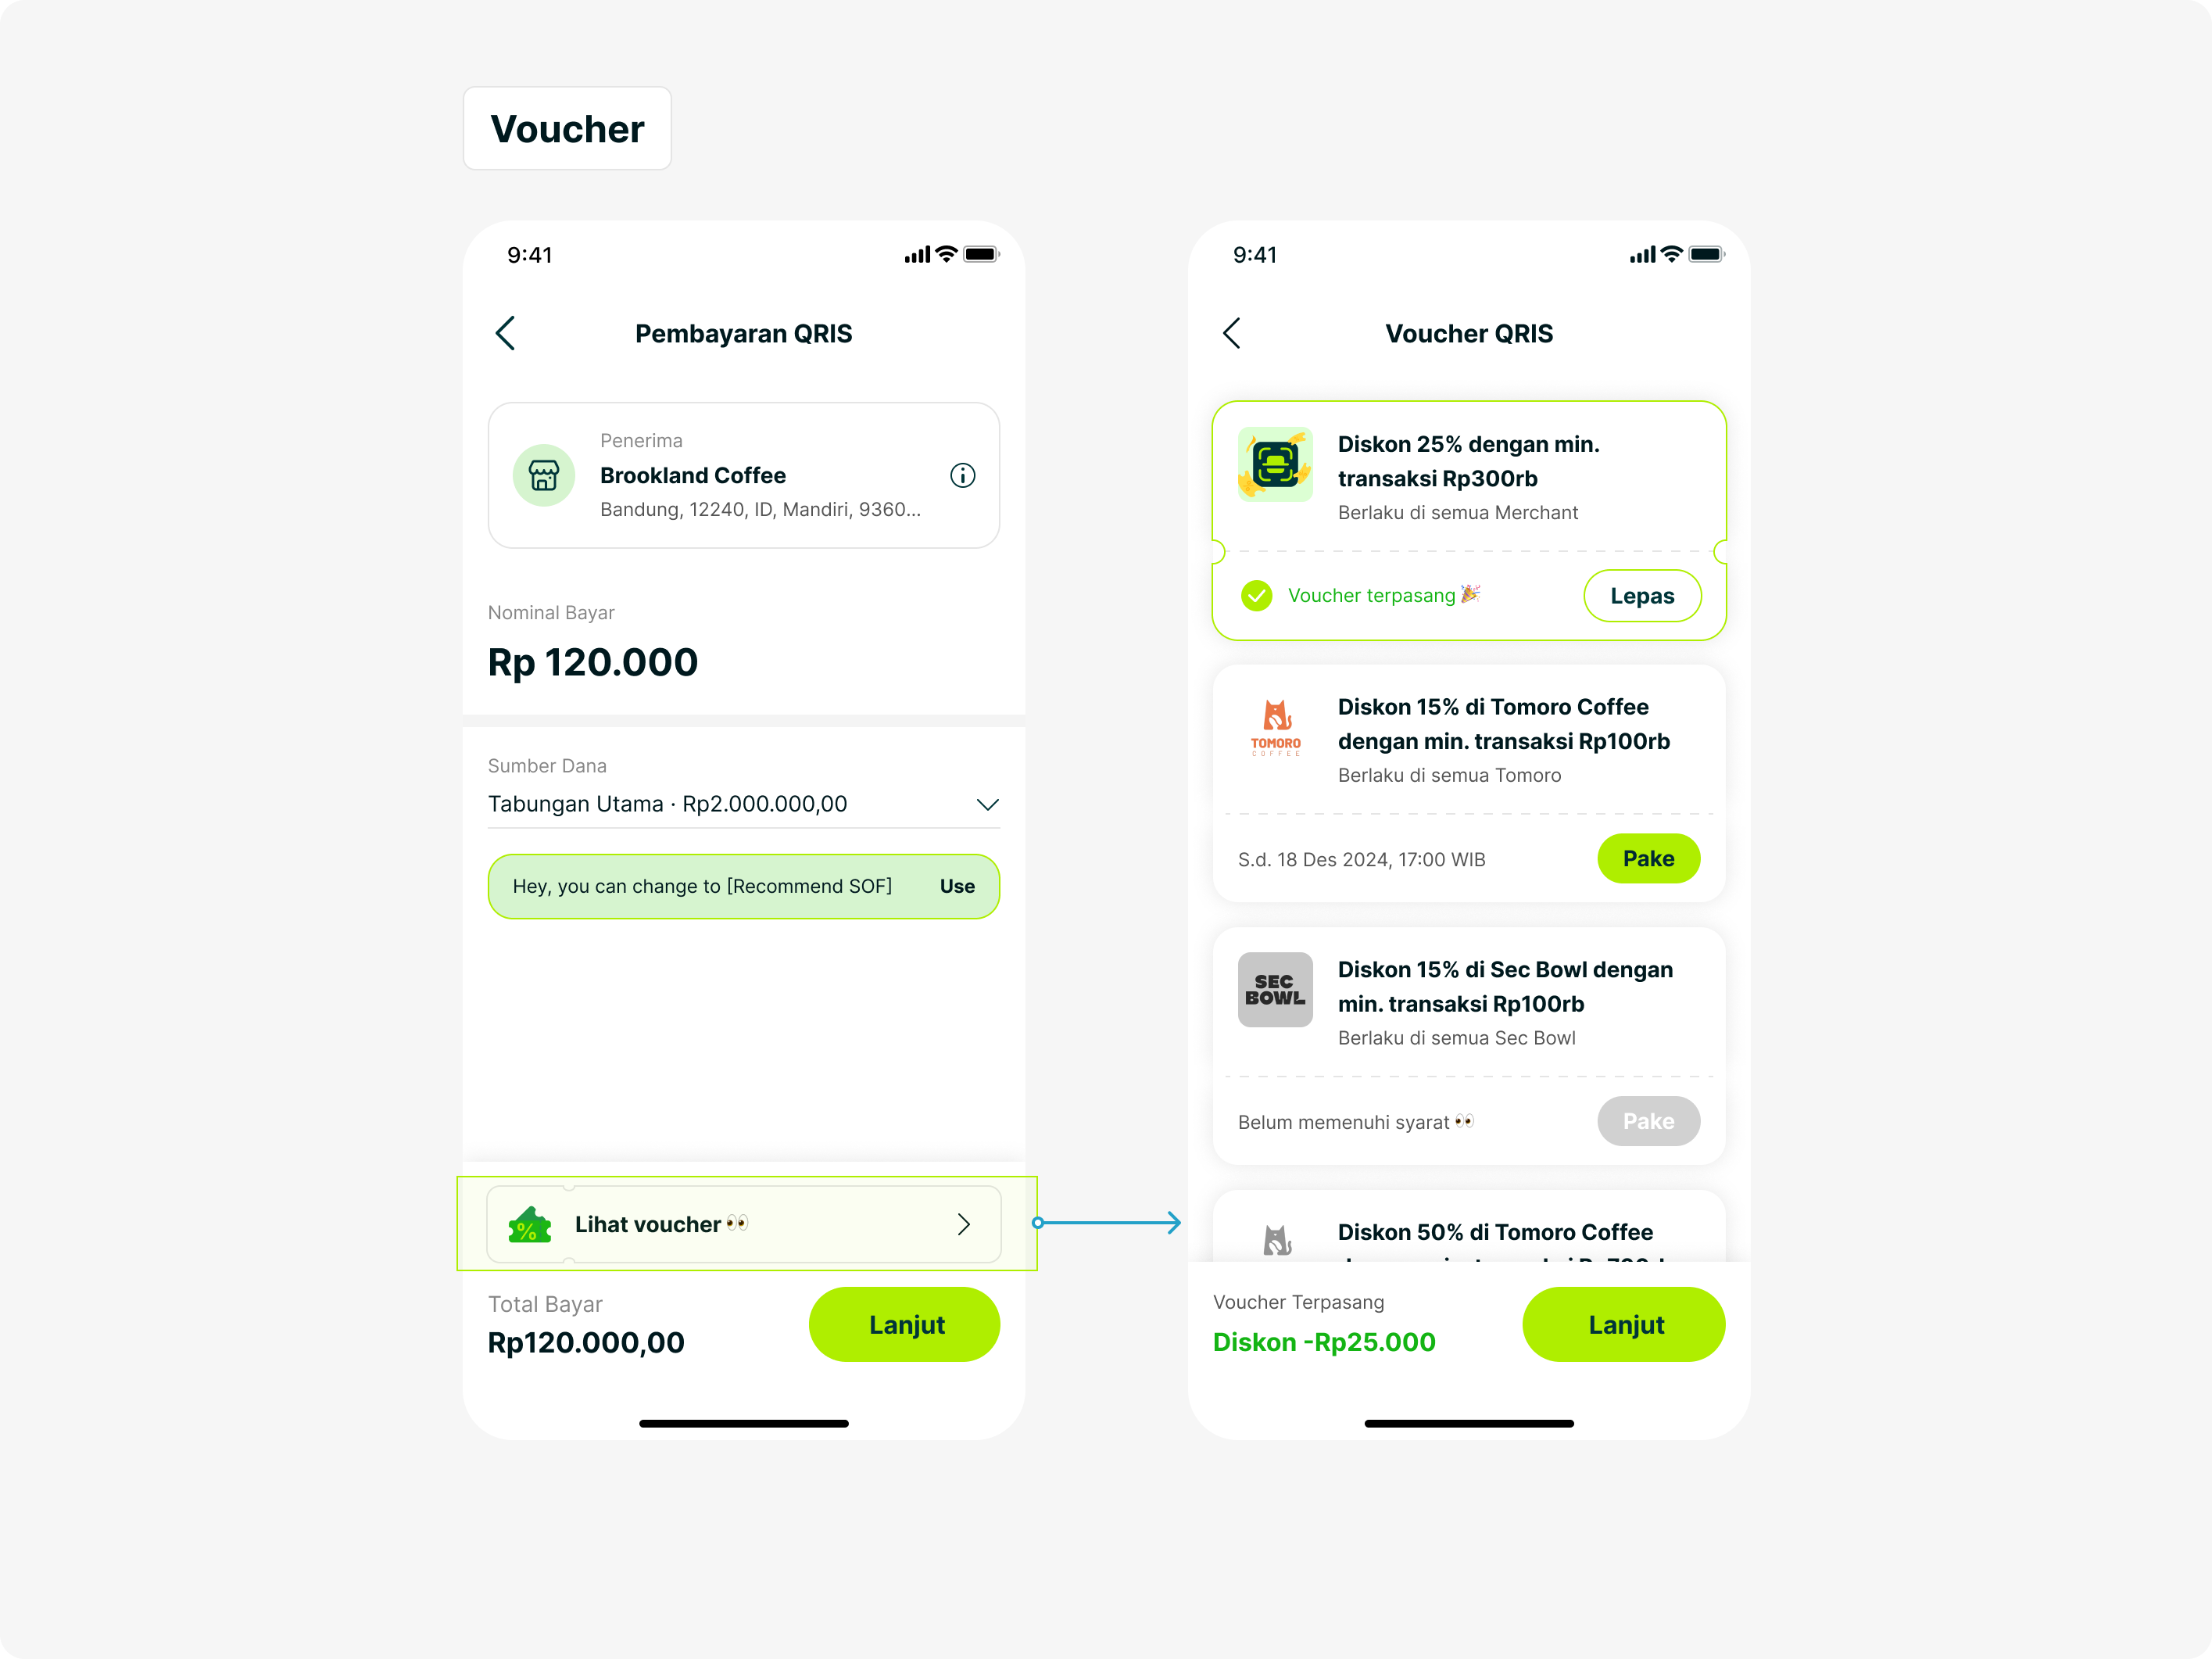
I led the end-to-end design of QRIS payments, from the core transaction experience to direct discounts and future payment capabilities.
One of the more interesting challenges was balancing flexibility with simplicity. How could we give customers more control over their source of funds without complicating their savings experience?
Beyond individual payment flows, I also explored how QRIS could support new use cases as the product continued to evolve.
Impact
XX%
QRIS transaction volume growth.
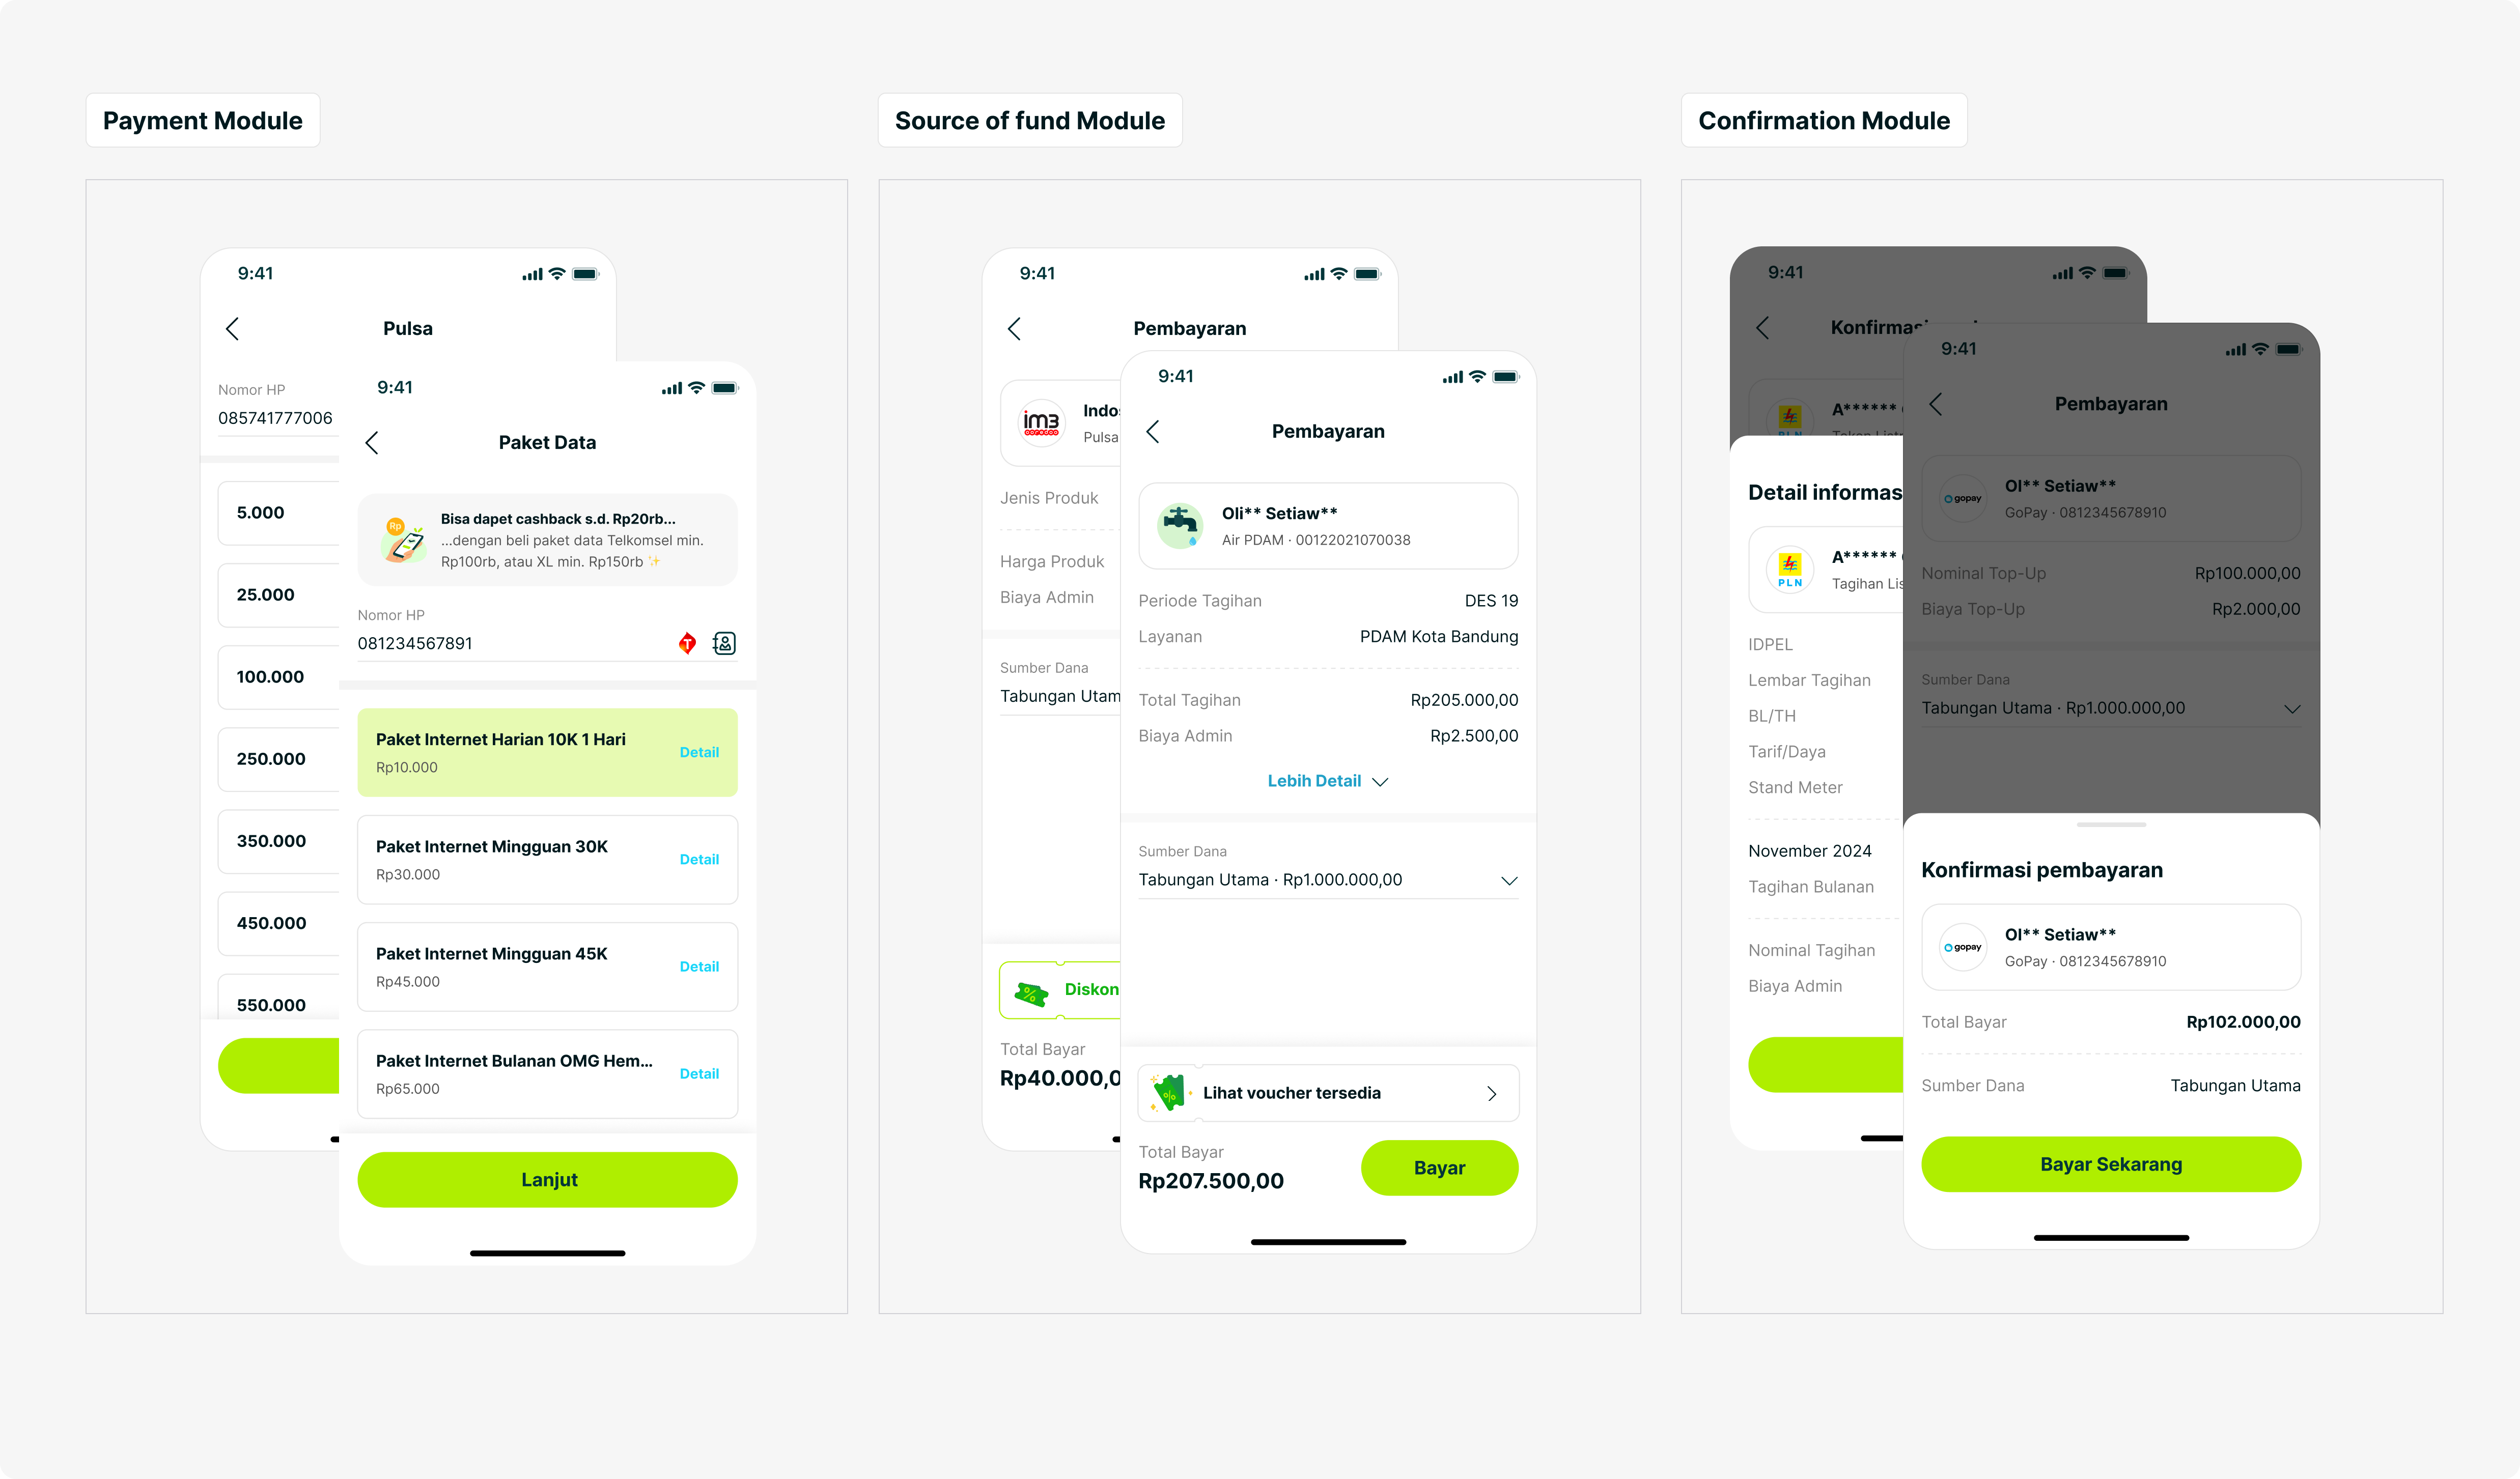
Bill Payments: One Experience, Different Payment Needs
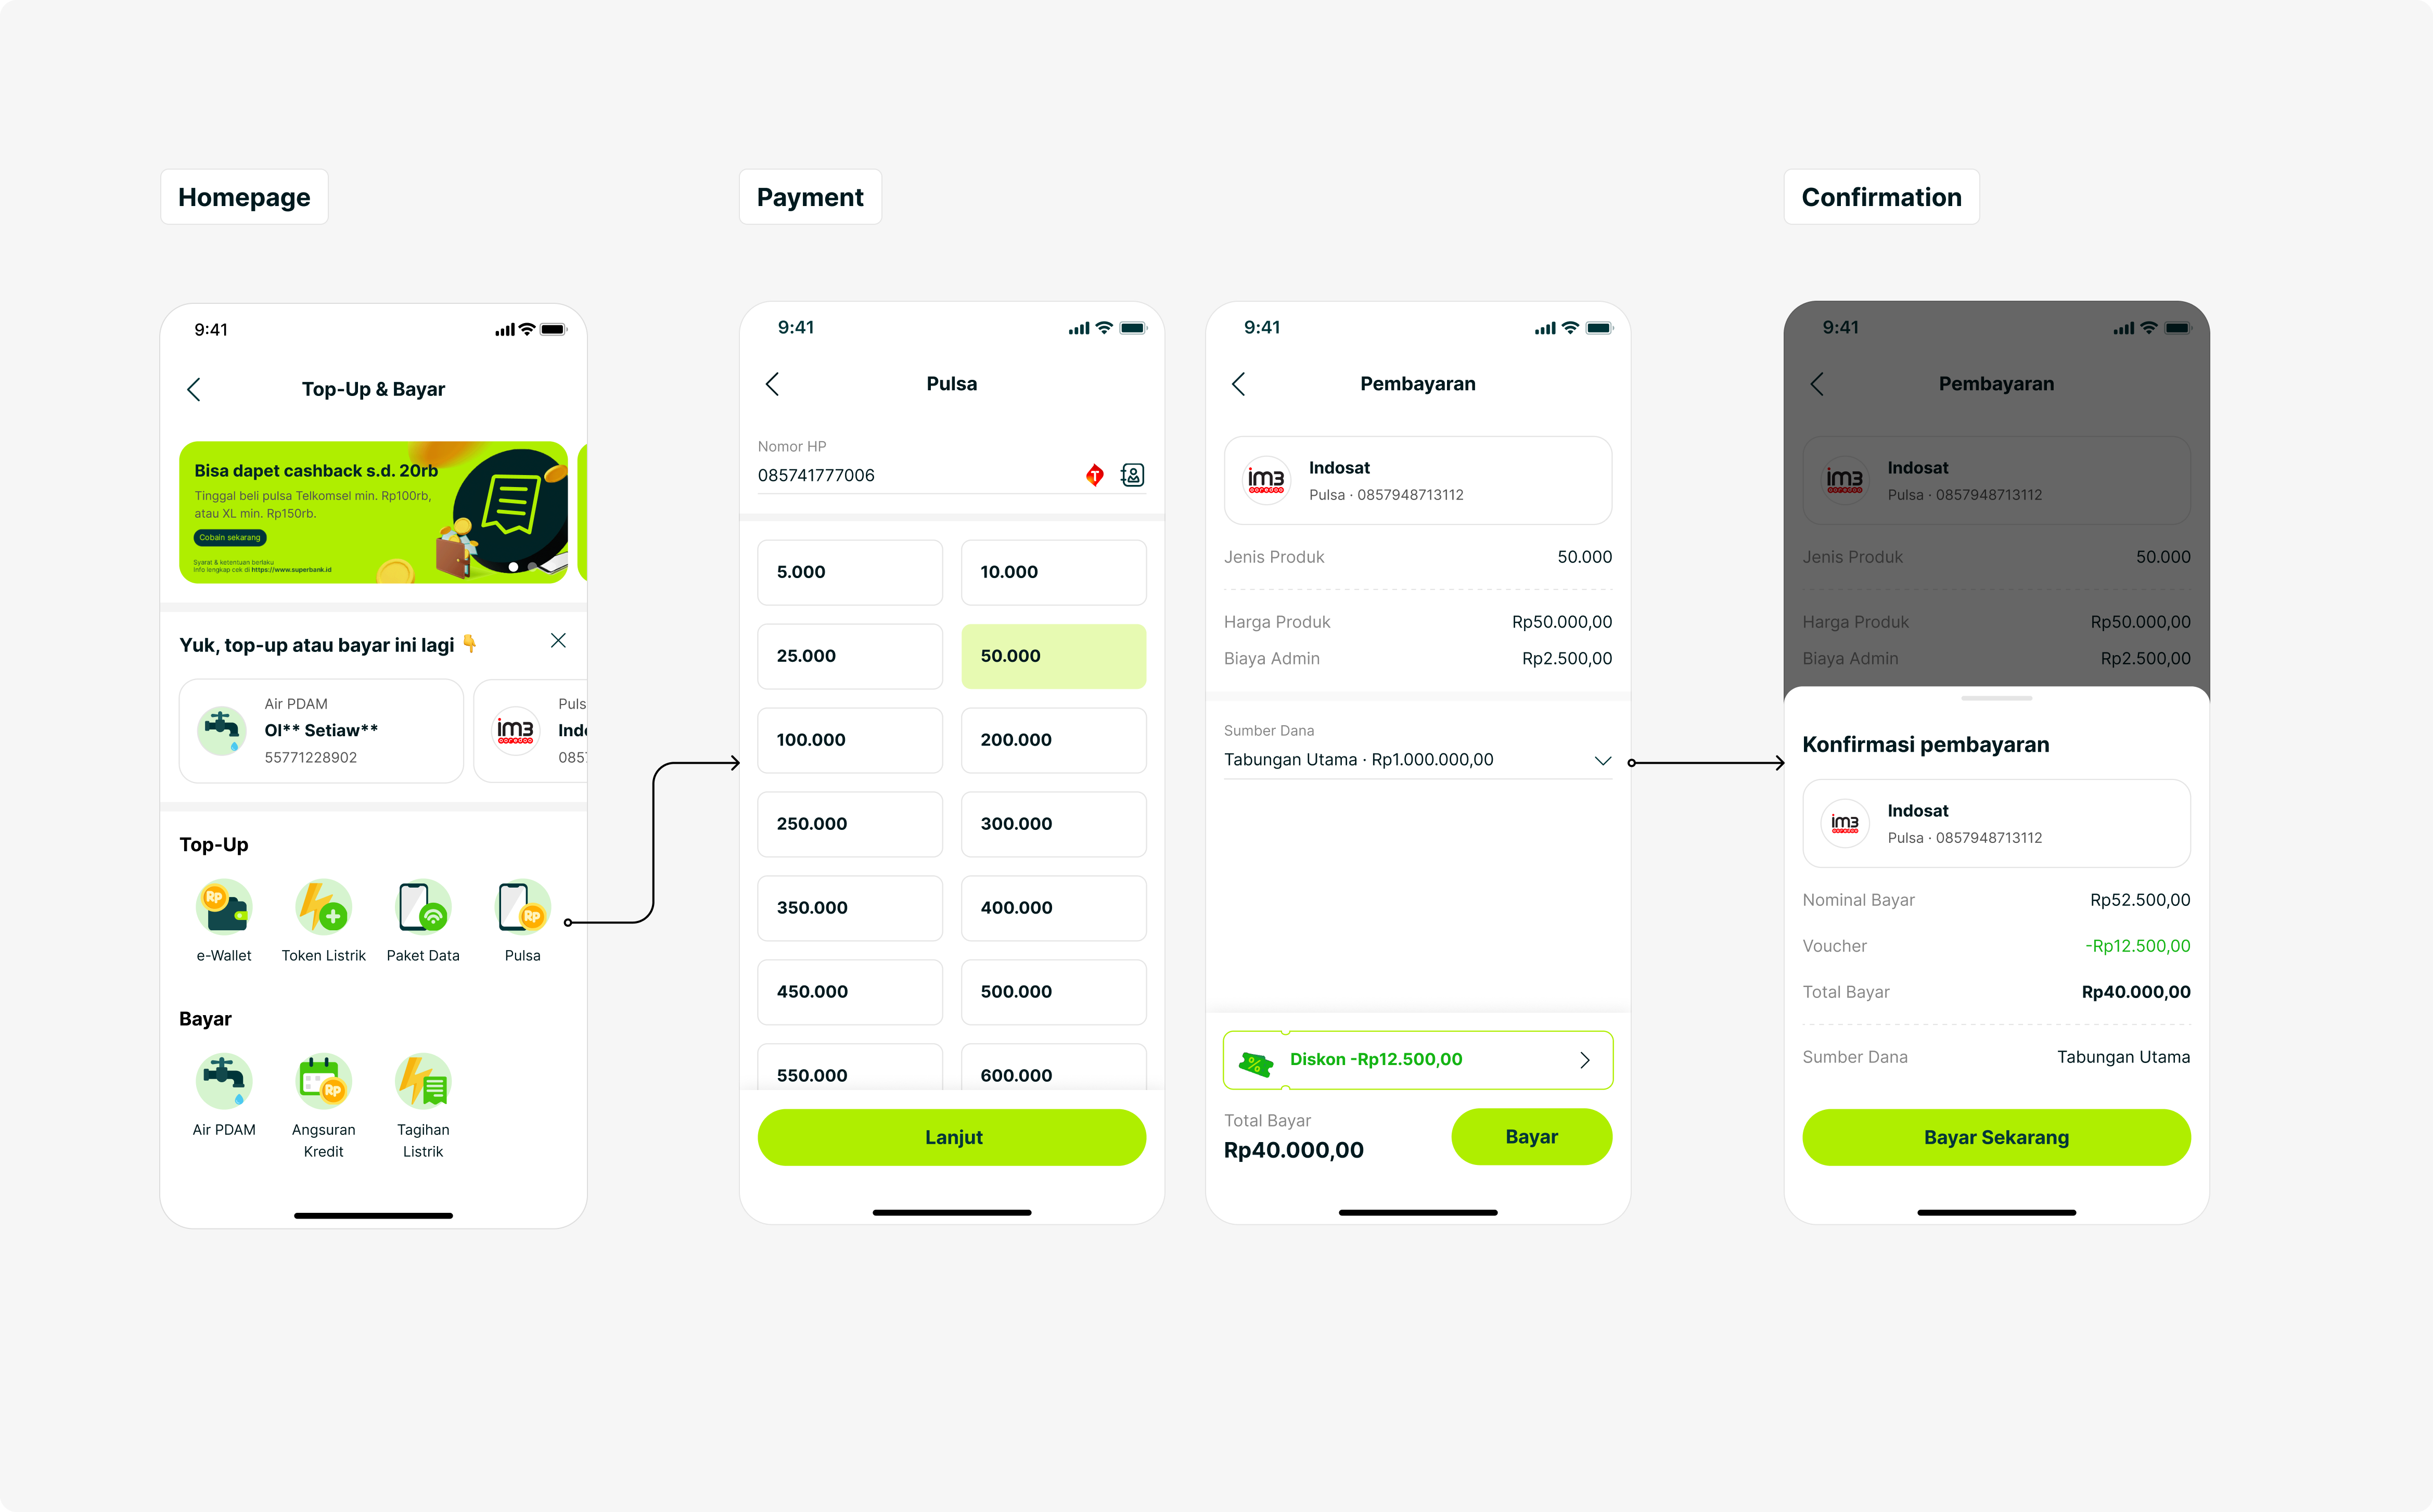
Bill payments brought a different kind of complexity. Each category could have its own providers, requirements, and transaction flows, making it difficult to maintain a consistent experience.
The challenge wasn't just designing another payment feature. It was figuring out how to support different payment needs without creating a fragmented experience.
I led the design of bill payments, focusing on consistent interaction patterns and a scalable structure that could accommodate additional payment categories in the future.
Impact
XX%
Bill payment transaction volume growth.
Beyond Individual Features
What building a bank from zero taught me.
Building Superbank from its early days taught me that good design goes beyond individual features.
As the product grew, I learned how every decision could affect the broader ecosystem, from acquisition and lending to everyday payments.
It pushed me to think beyond screens, balance speed with scalability, and connect customer needs with business goals and technical constraints.
Good design isn't just about solving today's problems. It's about understanding what your decisions make possible next.
I'm grateful to have been part of this journey and to the people who trusted me along the way.